
Micron Technology, Inc.
Micron is one of the world’s leading manufacturers of memory semiconductors and memory solutions. Its product portfolio includes DRAM, NAND, and NOR memory, among others. These technologies are used in data centers, PCs, mobile devices, vehicles, and industrial applications.
An increasingly important part of Micron’s development is the company’s position within AI infrastructure. High Bandwidth Memory (HBM) is gaining strategic importance, as AI accelerators require significantly more powerful and larger memory solutions than traditional computer systems.
Micron is already shipping HBM4 in high volumes while continuing to advance HBM4E. Mass production is expected to begin in 2027.
Valuation
This analysis assesses Micron in line with the MUMAK UMBRELLA Strategy.
The valuation is carried out across five decision phases: Geopolitics, Industry, Fundamentals, Market Sentiment, and Technical Analysis.
The goal is not to predict the future exactly. The goal is orientation. We classify facts, show the interdependencies, and structure a transparent decision logic.
We explain – you decide.
Geopolitics
Classification
Micron operates in one of the most strategically important areas of the global technology industry. Semiconductors are increasingly becoming part of national industrial and security policy. In particular, the US and other countries are seeking to expand domestic semiconductor production and reduce dependence on globally concentrated supply chains.
At the same time, the geopolitical environment provides Micron with significant support in expanding its production capacities in the US. The company is accelerating its US production strategy and plans to invest more than $250 billion in production and technology in the United States by 2035.
In the long term, Micron aims to manufacture around 40% of its DRAM output in the US.
Government support also plays an important role. Under the CHIPS Act, Micron has been awarded funding of up to around $6.4 billion to expand its production capacities in Idaho, New York, and Virginia.
The first new factory in Idaho is expected to begin DRAM production in 2027.
Opportunities
- AI infrastructure continues to gain strategic importance.
- US semiconductor policy supports the expansion of domestic production.
- CHIPS Act funding makes capacity expansion easier.
- Greater production in the US could improve security of supply.
Risks
- Semiconductors remain exposed to geopolitical tensions.
- Trade restrictions can affect international end markets.
- Supply chains remain highly interconnected globally.
- Expanding state-of-the-art production capacity requires substantial investment.
Key takeaway: Micron is strategically well positioned within the trend toward greater domestic semiconductor production and the build-out of AI infrastructure.
MUMAK.me rating phase 1: Positive = 1 MUMAK
Micron Technology, Inc.
Industry
Context
The memory semiconductor industry continues to benefit from strong structural demand, driven in particular by AI and data centers.
Micron is primarily active in the DRAM and NAND markets and is further expanding its position in High Bandwidth Memory.
The global DRAM market remains highly concentrated. Samsung Electronics, SK Hynix, and Micron dominate the market, while Chinese competitor CXMT is gradually gaining relevance.
Competition in the HBM segment is particularly relevant. SK Hynix has built a strong position here, while Samsung also remains a major global competitor.
Micron in a valuation comparison
| Metric | Micron 2026e | Industry Average* | Valuation |
|---|---|---|---|
| P/E ratio | 13.8x | approx. 15–25x | Lower valuation |
| EBIT margin | 76% | approx. 35–65% | Stronger |
| Net margin | 64% | approx. 25–55% | Stronger |
| Revenue growth 2026e | approx. 247% | approx. 20–80% | Stronger |
*The peer group includes Samsung Electronics, SK Hynix, and ChangXin Memory Technologies (CXMT). The ranges are for orientation and are only comparable to a limited extent due to different business models and corporate structures.
Source: MarketScreener consensus estimates and market data, September 2026.
The most important structural growth driver remains the continued build-out of AI infrastructure.
Recent data from the memory market also supports this view. According to data cited by Barron’s, DRAM prices rose by around 6% in July, while NAND prices increased by about 9%.
This keeps the near-term market backdrop supportive for memory manufacturers ahead of Micron’s next quarterly results.
However, the memory industry remains highly cyclical. Historically, phases of high profitability have often led to capacity expansion, which can ultimately result in oversupply and pressure on memory prices.
Opportunities
- AI is strongly driving demand for memory solutions.
- HBM expands the addressable market.
- Limited supply supports memory prices.
- Data centers increasingly require higher memory capacities.
- Micron has a strong global market position.
Risks
- The memory market remains highly cyclical.
- SK Hynix remains a key competitor in HBM.
- Samsung remains a strong global competitor.
- CXMT is becoming increasingly relevant.
- Future capacity expansion could weigh on prices.
Key takeaway: Micron continues to operate in an attractive market environment for memory semiconductors.
MUMAK.me rating phase 2: Positive = 1 MUMAK
Micron Technology, Inc.
Fundamentals
Context
Micron’s fundamental trajectory has improved significantly. The company is benefiting from higher memory prices as well as sharply rising demand from AI and data-center applications.
At the same time, the historical track record shows how cyclical Micron’s business can be. Revenue rose sharply through 2022, but the downturn in the memory market led to a significant revenue decline and a net loss in 2023.
Since then, the business has rebounded meaningfully. In fiscal year 2025, Micron generated revenue of around $37.4 billion, while net income came in at roughly $8.5 billion.
Financial performance
The latest figures for Q3 2026 showed another clear acceleration in revenue and profitability.
| Metric | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Revenue | $41.46 billion | $9.30 billion | +346% |
| Gross margin | 81.9% | 36.5% | +45.4 pp |
| Operating income | $30.73 billion | $1.96 billion | +1,468% |
| Net income | $28.24 billion | $1.89 billion | +1,394% |
| EPS | $24.58 | $1.68 | +1.363 % |
Source: Micron Q3 2026 results.
Revenue growth is primarily supported by higher memory prices, rising data-center demand, and strong HBM shipments.
Outlook Q4 2026
Management’s outlook suggests that the current momentum could continue.
| Q4 2026 Guidance | Outlook |
|---|---|
| Revenue | $50.0 billion ± $1.0 billion |
| Gross Margin | approx. 86% |
| Operating Expenses | approx. $1.86 billion |
| EPS | $30.73 ± $1.00 |
Source: Micron Q3 2026 results
Micron also confirmed that HBM4 is already being shipped in high volumes, while development of HBM4E continues to progress. Mass production is expected to begin in 2027.
The next key confirmation of the fundamental trend will therefore come from Micron’s Q4 2026 results on September 30. Current analyst expectations are close to Micron’s guidance. The FactSet consensus cited by Barron’s expects revenue of around $50.4 billion and adjusted EPS of $30.89.
Opportunities
- AI and HBM are strongly driving revenue growth.
- High memory prices support margins.
- Cash generation has improved significantly.
- HBM4 strengthens Micron’s product positioning.
- HBM4E could provide an additional growth driver from 2027.
Risks
- Current margins are exceptionally high.
- The memory business remains cyclical.
- Expectations have risen significantly.
- Expanding production capacity requires substantial investment.
- Falling memory prices could weigh on future performance.
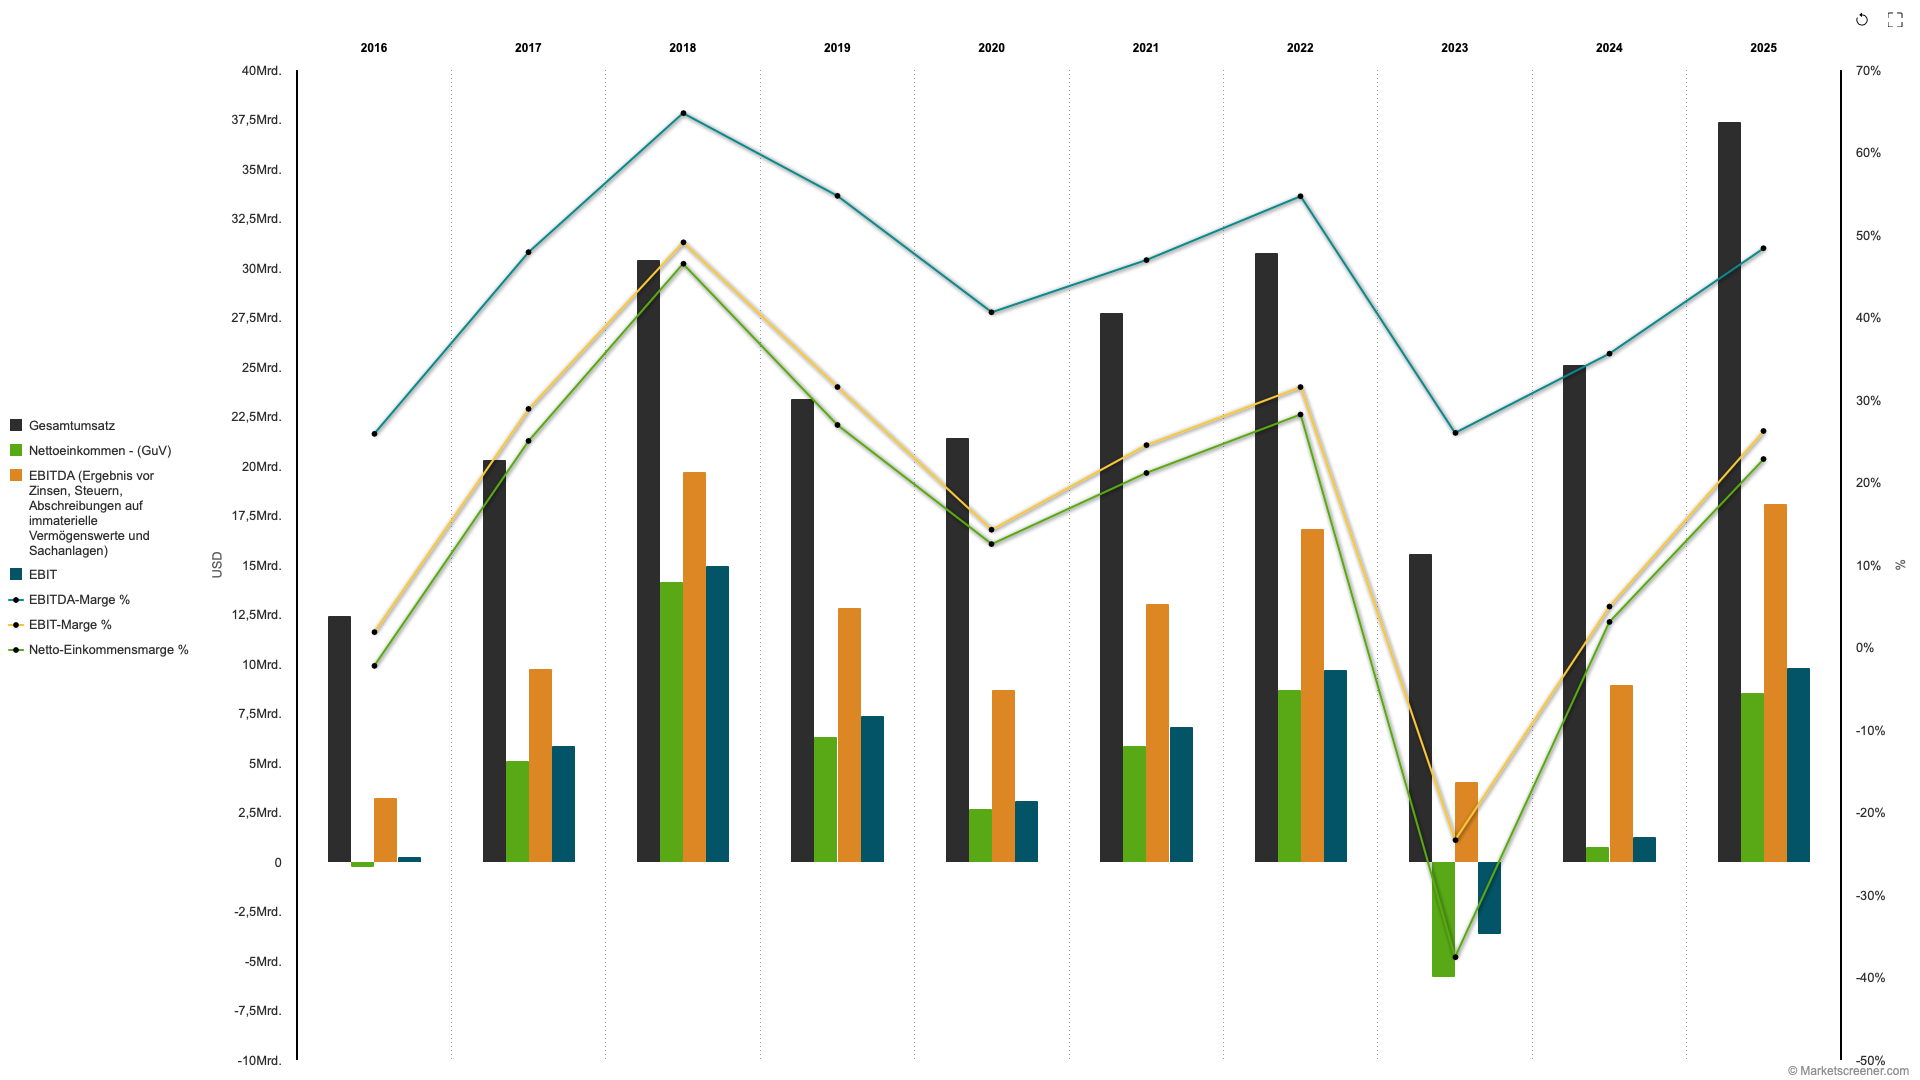
Micron’s fundamentals show the strong cyclical recovery of the memory business. After the downturn in 2023, revenue recovered to $25.1 billion in 2024 and reached $37.4 billion in 2025. Profitability improved even more significantly: Net profit rose to $8.5 billion in fiscal year 2025, while the operating margin reached 26.1%.
The longer-term trend also illustrates Micron’s cyclical earnings profile: Phases of high margins can be followed by significant declines when demand for memory solutions and memory prices fall. Currently, however, the trend in revenue and profitability is clearly upwards.
Key takeaway: Micron’s fundamentals remain strong.
MUMAK.me Valuation Phase 3: Positive = 1 MUMAK
Micron Technology, Inc.
News, analysts, and market sentiment
Context
The news flow around Micron remains positive.
Recent data from the memory market supports the fundamental picture. DRAM and NAND prices have continued to rise, while demand for high-performance memory solutions for AI infrastructure remains strong.
The next key company-specific catalyst will be Micron’s Q4 2026 results on September 30.
Analyst consensus
| Average Recommendation | BUY |
| Number of Analysts | 49 |
| Average Price Target | approx. 1,513 USD |
| Distance to Average Target | approx. +51% |
| Highest Price Target | 2,200 USD |
| Lowest Price Target | 361 USD |
Source: MarketScreener, September 9, 2026.
Based on the latest closing price of around $1,000, the average price target implies potential upside of roughly 51%.
There have also been several new analyst updates recently. Bernstein reiterated its Buy rating on September 8 with a price target of $1,300. BMO Capital Markets initiated coverage with an Outperform rating and also a price target of $1,300.
Market sentiment
Market sentiment toward Micron remains positive, but is increasingly shaped by high expectations.
After its summer correction, the stock has recently climbed back above $1,000. Shares in memory technology and AI infrastructure have also regained momentum, as the market once again focuses more strongly on demand from AI data centers.
At the same time, Micron shares have already posted a very strong performance in 2026. This makes the upcoming earnings releases even more important.
Opportunities
- Analyst consensus remains clearly positive.
- HBM4 supports the AI growth story.
- Memory price trends remain supportive.
- Q4 guidance signals continued momentum.
- AI infrastructure continues to support demand for memory solutions.
Risks
- Market expectations are exceptionally high.
- Analyst price targets show a wide range.
- Memory prices remain a key driver.
- A weaker HBM outlook could weigh on sentiment.
- Q4 results could lead to elevated volatility.
Key takeaway: Market sentiment toward Micron remains positive.
MUMAK.me Evaluation Phase 4: Positive = 1 MUMAK
Micron Technology, Inc.
Technical analysis
Context
The chart setup for Micron Technology shares has improved significantly recently. After the sharp correction from the high at around $1,210, the price stabilized in the $800–900 range and has recently formed **higher lows**.
At the time of this research, Micron is trading at around **$1,016** and thus clearly above the middle Bollinger Band at roughly $950.50.
Performance over the past weeks/months
(As of: September 8, 2026)
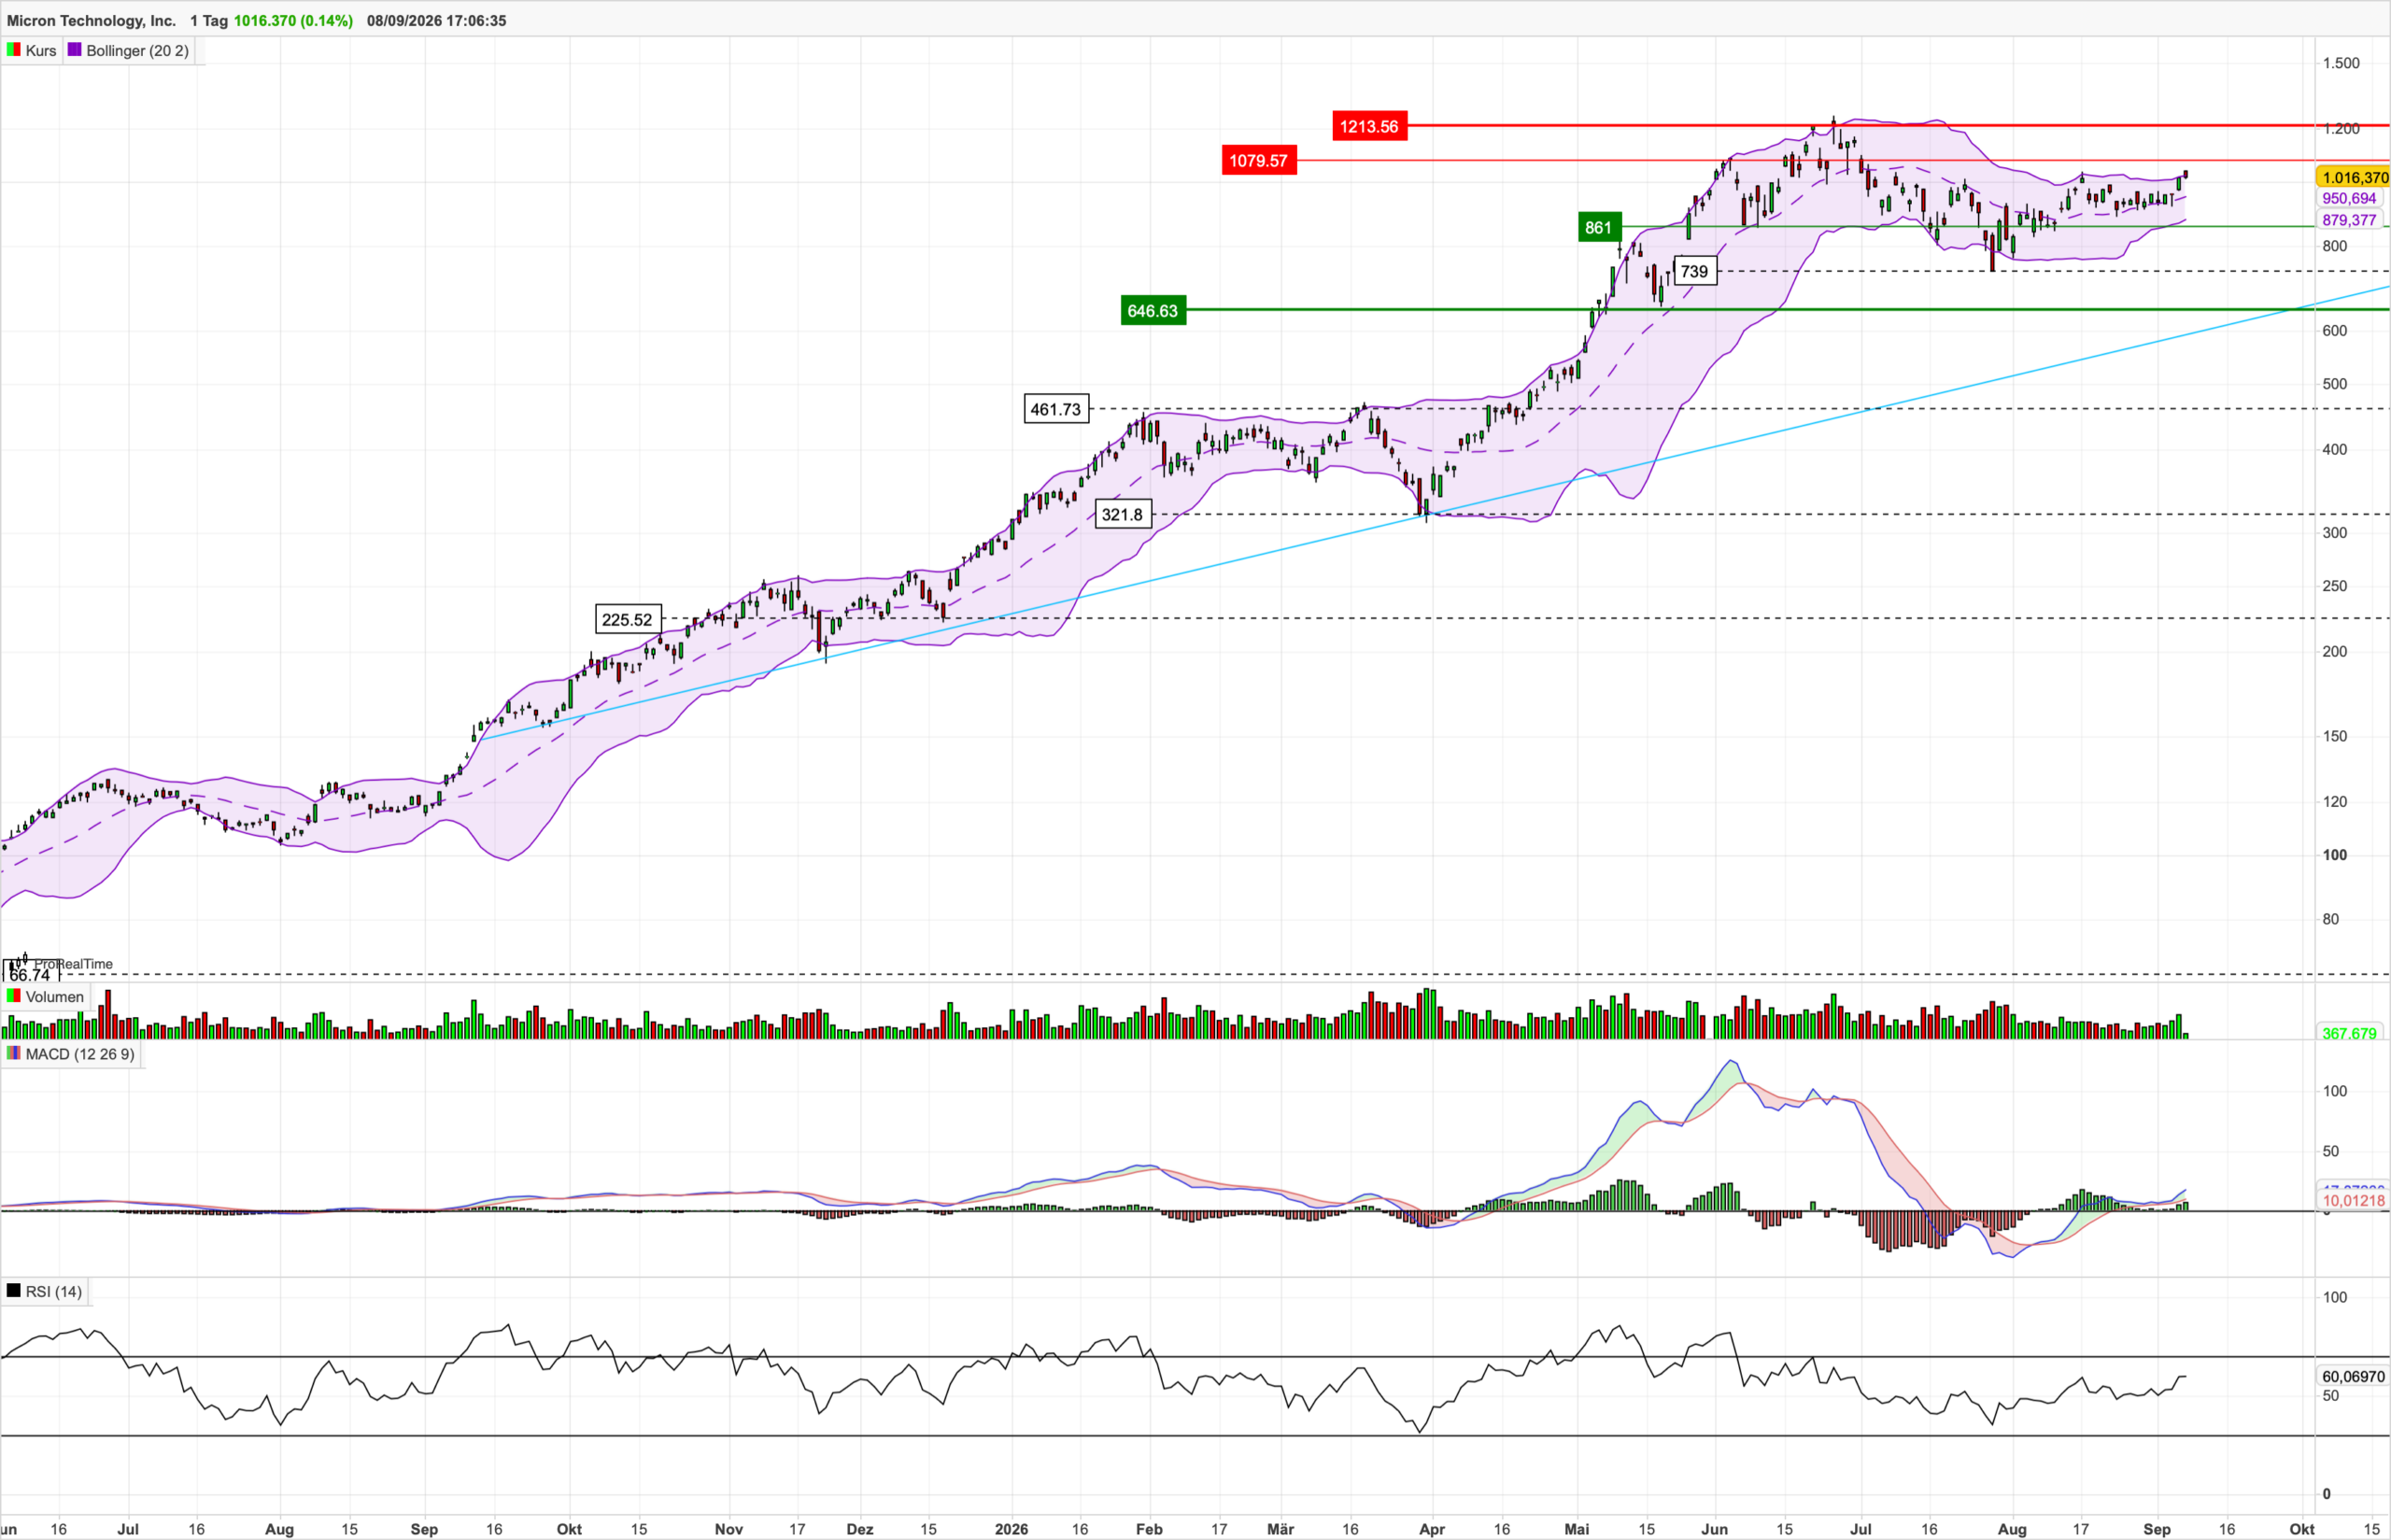
Technical picture remains positive
| Indicator | Rating | Interpretation |
| RSI (14) | Positive | Around 60 – good momentum, not yet overbought |
| MACD | Positive | Bullish signal and increasing dynamic |
| Bollinger Bands | Positive | Price above the middle band |
Key levels for Micron shares
The next decisive resistance is at $1,080. A sustained breakout above it could enable a retest of the high at $1,210.
On the downside, the area around $950 is the first key support. Below that comes the zone between $879 and $861.
Opportunities
- Base formation after the summer correction
- rising lows
- positive RSI and MACD signals
- a breakout above $1,079 could trigger fresh upside momentum
Risks
- resistance at $1,080
- a short-term pullback at the upper Bollinger Band is possible
- below $950, the technical picture would weaken again
Key takeaway: Micron shares currently show a positive technical setup. The decisive factor now is a breakout above $1,080. If that happens, the prior high at around $1,210 could come back into focus.
MUMAK.me rating phase 5: Positive = 1 MUMAK
Micron Technology, Inc.
What currently supports Micron?
- AI infrastructure is strongly driving demand for high-performance memory solutions.
- HBM is emerging as an important structural growth driver.
- Micron has a strong position in the global DRAM market.
- Revenue, margins, and profits have improved significantly.
- HBM4 is already being shipped in high volumes.
- HBM4E offers additional growth potential from 2027.
- Memory prices are currently providing additional support.
- Analyst sentiment remains positive.
What currently argues against Micron?
- The memory market remains highly cyclical.
- Current profitability is exceptionally high.
- Market expectations have risen significantly.
- Expanding production capacity requires substantial investment.
- Falling memory prices could weigh on margins.
- The stock has already posted a very strong performance in 2026.
What we are watching
- Progress on HBM4E toward the planned start of mass production in 2027
- DRAM and NAND price trends
- Micron’s Q4 2026 results on September 30
Summary
The overall picture across all five MUMAK phases is positive. Micron combines strong fundamental momentum with an increasingly constructive technical setup.
From a fundamental perspective, AI infrastructure and HBM remain the key growth drivers. At the same time, high profitability and rising market expectations mean that memory price trends, HBM demand, and the upcoming Q4 results remain particularly important.
The positive rating across all five MUMAK phases and the constructive technical picture supported the inclusion of Micron Technology in the UMBRELLA Strategy.
Rating According to the MUMAK Method
| Category | Rating |
|---|---|
| Geopolitics | Positive |
| Industry | Positive |
| Fundamentals | Positive |
| News & Sentiment | Positive |
| Technical Analysis | Positive |
Overall Rating


