

Alphabet Inc.
Valuation
This analysis evaluates Alphabet according to the MUMAK UMBRELLA Strategy.
The valuation is carried out across five decision phases: Geopolitics, Industry, Fundamentals, Market Sentiment, and Technical Analysis.
The goal is not to predict the future exactly. The goal is orientation. We classify facts, show the interdependencies, and structure a transparent decision logic.
We explain – you decide.
Geopolitics
Classification
Alphabet is a central provider in internet search, digital advertising, cloud infrastructure, mobile software, and artificial intelligence. As a result, the group holds strategic importance in the global competition for technological leadership in AI, computing capacities, data, and digital standards.
The USA benefits from Alphabet’s research base and the company’s investments in domestic infrastructure. At the same time, governments increasingly view cloud and AI capacities as strategic resources.
However, the group’s size and dominant market position lead to ongoing regulatory risks. Antitrust measures in the USA, the enforcement of the EU Digital Markets Act, data protection regulations, export controls, and local data storage requirements can influence product design, distribution, and monetization.
Opportunities
- The USA’s leading position in AI and cloud infrastructure strengthens Alphabet’s strategic importance.
- The globally increasing demand for sovereign and secure cloud capacities can create additional business opportunities in the enterprise customer segment.
- Alphabet connects its own models, TPUs, cloud capacities, and direct access to end customers within its AI infrastructure.
- Waymo and other long-term oriented projects enable participation in strategically important future technologies.
Risks
- Antitrust measures in the USA and Europe could restrict the preferred placement of proprietary services, the bundling of offerings, and certain practices in the ad tech business.
- The regulation of digital markets can increase compliance costs and reduce entrepreneurial flexibility in Google Search, Google Play, and the advertising business.
- Export controls and tensions between the USA and China can limit access to customers, suppliers, and markets for advanced technologies.
- Differing regulations on data sovereignty, data protection, and AI security can delay the introduction of new products.
Key takeaway: Alphabet’s strategic position in AI, cloud infrastructure, and digital technologies outweighs regulatory and geopolitical risks, supporting a positive geopolitical assessment.
MUMAK.me Valuation Phase 1: Positive = 1 MUMAK
Alphabet Inc.
Industry
Classification
Alphabet operates in digital advertising, internet search, cloud computing, generative AI, video, and autonomous driving. The industry benefits from structural growth in online activities, enterprise cloud migration, and increasing use of artificial intelligence.
Alphabet has a strong global reach with Google Search, YouTube, Android, Chrome, and Workspace. At the same time, Google Cloud forms a second significant growth driver.
However, competition is intense: Microsoft, Amazon, Meta, OpenAI, and other AI platforms compete for users, advertisers, enterprise contracts, and developer ecosystems.
Valuation Comparison: Alphabet and Major Technology Platforms
| Metric | Alphabet 2026e | Peer Group* | Valuation |
|---|---|---|---|
| P/E Ratio | 17.2x | approx. 20–35x | Lower Valuation |
| EBIT Margin | 34.5% | approx. 25–45% | Within Range |
| Revenue Growth 2026e | 23.8% | approx. 10–25% | Stronger |
| Free Cash Flow Margin | 1.6% | approx. 15–35% | Weaker |
*The peer group includes Microsoft, Amazon, and Meta. Industry ranges serve as guidance. Alphabet estimates: MarketScreener, September 2026.
Opportunities
- AI features can strengthen the use of Google Search and the relevance of displayed advertising.
- Google Cloud can gain further market share through AI infrastructure and AI solutions for businesses.
- YouTube and subscription services diversify the revenue base beyond the traditional search engine business.
- TPUs and the broader Gemini ecosystem can deepen customer and developer loyalty to Alphabet’s platform.
Risks
- AI assistants can change user behavior and weaken the traditional monetization of internet search.
- The expansion of cloud and AI infrastructure requires exceptionally high investments.
- Competition for AI models, chips, skilled workers, and enterprise contracts remains intense.
- Demand for digital advertising continues to be sensitive to economic developments and changes in measurement methods and data protection regulations.
Key takeaway: Structural growth in AI, cloud, and digital advertising supports a positive industry valuation despite intense competition and high capital intensity.
MUMAK.me Valuation Phase 2: Positive = 1 MUMAK
Alphabet Inc.
Fundamentals
Classification
Alphabet achieved strong operating results in the second quarter of 2026. Revenue increased by 24% to $119.80 billion. Google Services recorded growth of 15%, while Google Cloud’s revenue increased by 82%.
Reported net income rose significantly as other income included a gain from equity investments of $99.0 billion. This non-operating effect substantially increased GAAP earnings and should not be considered recurring operating profit.
At the same time, free cash flow was negative in the second quarter as capital expenditures rose to $44.92 billion. This reflects the rapid expansion of AI infrastructure.
Financial Performance
| Metric | Q2 2026 | Q2 2025 | Change |
|---|---|---|---|
| Revenue | $119.80 billion | $96.43 billion | +24% |
| Operating Income | $40.77 billion | $31.27 billion | +30% |
| Net Income | $112.19 billion | $28.20 billion | +298% |
| Diluted Earnings Per Share | $9.11 | $2.31 | +294% |
| Operating Cash Flow | $39.07 billion | $27.75 billion | +41% |
| Free Cash Flow | −$5.86 billion | $5.30 billion | Turned negative |
Segment Performance
| Segment | Revenue Q2 2026 | Growth | Operating Income |
|---|---|---|---|
| Google Services | $94.54 billion | +15% | $39.54 billion |
| Google Cloud | $24.77 billion | +82% | $8.81 billion |
| Other Bets | $0.38 billion | +2% | −$1.80 billion |
| Alphabet Total | $119.80 billion | +24% | $40.77 billion |
Source: Alphabet Q2 2026 Earnings Report, July 22, 2026.
Historical Financial Performance
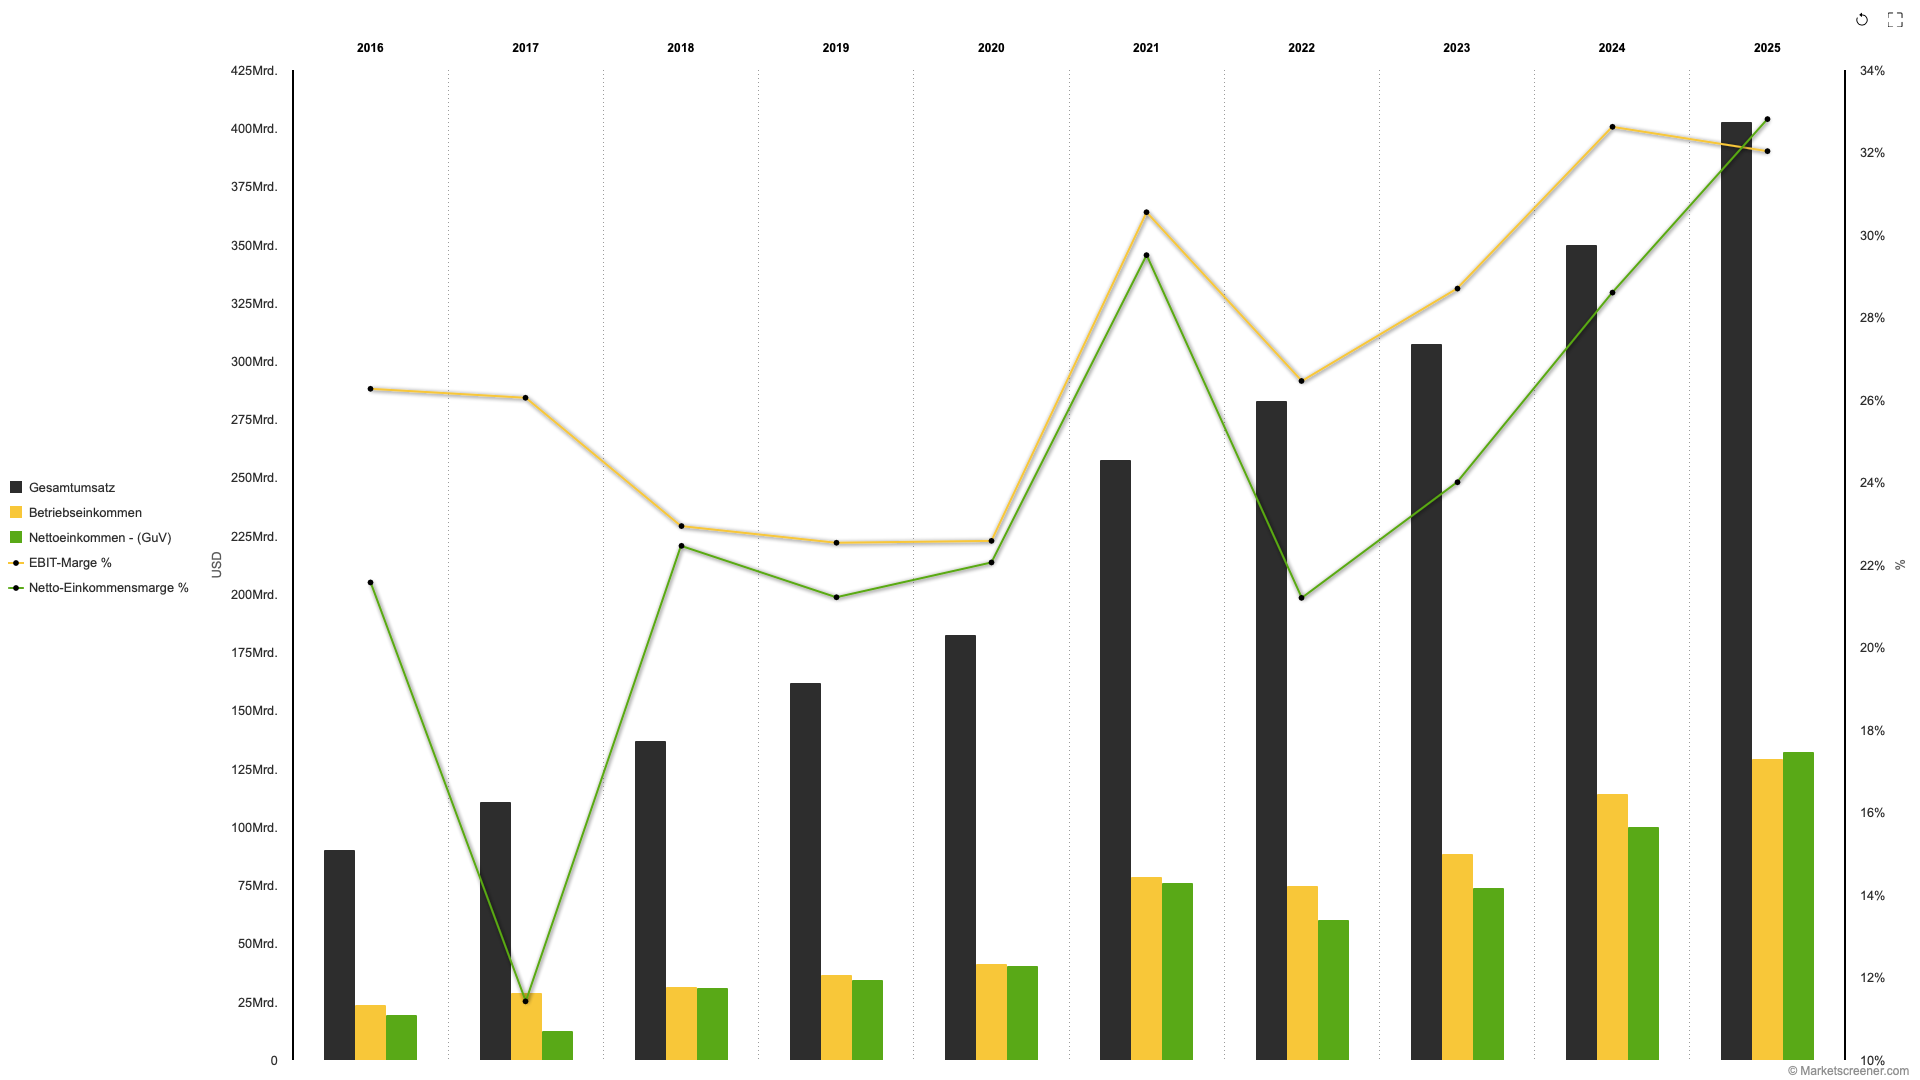
Alphabet’s revenue and operating income have continuously increased since 2022. In 2025, revenue reached $402.84 billion, while EBIT increased to $129.04 billion. The EBIT margin recovered to around 32%. This development was supported by cost discipline, growth in the advertising business, and increasing profitability of Google Cloud.
Financial Outlook
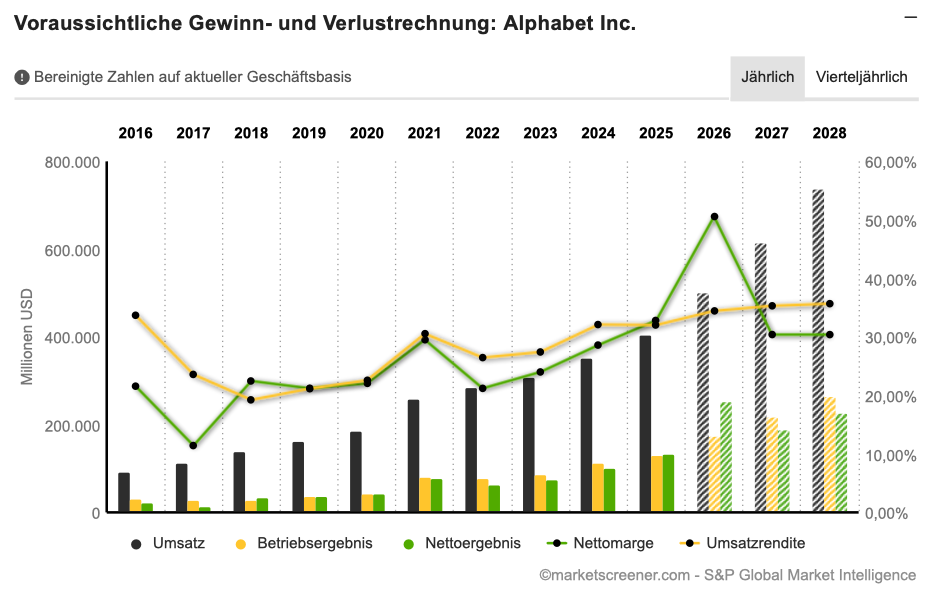
Market estimates indicate continued strong growth until 2028. Revenue is expected to increase due to the AI-powered evolution of Google Search, the growth of YouTube, and the expansion of Google Cloud.
Further improvement in operating margins is expected. However, free cash flow is likely to remain under pressure as the infrastructure program grows faster than operating cash flow. The 2026 net income forecast is also significantly distorted by the gain from equity investments recorded in the second quarter.
Key Findings
- Revenue increased by 24% in the second quarter, operating income by 30%.
- Google Cloud accelerated growth to 82% and significantly increased its earnings contribution.
- Google Search, YouTube, and subscription offerings contributed to Google Services’ growth.
- Reported net income was boosted by a high non-operating gain from equity investments.
- Investments in AI infrastructure pushed quarterly free cash flow below zero.
- The balance sheet continued to have significant liquidity reserves despite higher debt and capital expenditures.
Opportunities
- The growth and margin expansion of Google Cloud can further increase the segment’s earnings contribution.
- The integration of artificial intelligence can support the use of Google Search, advertising conversion, and subscription growth.
- Scaling across AI models, chips, data centers, and distribution channels can improve economic efficiency in the long term.
- The strong operating cash flow creates financial leeway to finance the AI investment cycle.
Risks
- Capital expenditures could remain at a high level longer than expected.
- A lower return on investments in AI infrastructure would burden free cash flow and valuation.
- Reported earnings are unusually strongly influenced by volatile gains from equity investments.
- Dependence on the advertising business and potential regulatory measures remain significant business risks.
Key takeaway: Strong operating growth, rising margins, and the dynamic development of Google Cloud support a positive fundamental valuation.
MUMAK.me Valuation Phase 3: Positive = 1 MUMAK
Alphabet Inc.
News, Analysts, and Market Sentiment
Classification
At the time of inclusion in the UMBRELLA Strategy, market sentiment towards Alphabet was positive. The second-quarter results showed broad-based operational momentum, while Google Cloud’s growth significantly accelerated and the use of Gemini continued to increase.
Analyst ratings were predominantly positive. Several analysis firms raised their price targets in September. Regulatory developments formed the main counterpoint.
On September 16, a US court ordered interoperability measures, data sharing, and prevention of discriminatory practices for Google’s ad tech business. In addition, six years of monitoring were stipulated.
In July, the European Commission also imposed DMA fines totaling EUR 890 million. These concerned the preferred placement of proprietary offerings in Google Search and restrictions on redirecting users to alternative offerings outside Google Play.
Key Developments
- Revenue increased by 24% in the second quarter, supported by Google Search, YouTube, Subscriptions, and Google Cloud.
- Google Cloud’s revenue increased by 82%, driven by growing demand for AI infrastructure and AI solutions for businesses.
- Gemini Enterprise was used by almost 90% of Fortune 100 companies, according to Alphabet.
- Gemini models processed 22 billion API tokens per minute, while the Gemini app reached 950 million monthly active users.
- A US court ordered behavioral measures for the ad tech business but did not require a structural breakup in the cited decision.
- Tigress raised Alphabet’s price target to $485 on September 18 and reaffirmed its “Strong Buy” rating. Evercore ISI raised the price target to $450 on September 17 and reaffirmed “Outperform”.
Analyst Consensus
| Average Recommendation | BUY |
| Number of Analysts | 61 |
| Average Price Target | approx. $429.5 |
| Distance to Average Target | approx. +21% |
| Highest Price Target | $515 |
| Lowest Price Target | $340 |
Source: MarketScreener, September 2026.
Interesting Fact
Google Cloud’s operating income more than tripled to $8.81 billion in the second quarter of 2026, while revenue increased by 82%. This development shows how quickly the demand for AI infrastructure can change the earnings contribution of Alphabet’s second-largest business segment.
Opportunities
- The further spread of Gemini can strengthen both private customer usage and enterprise demand.
- Higher price targets and a broad buy consensus support market confidence.
- The accelerated development of Google Cloud creates a clearer second growth engine alongside the advertising business.
- Behavioral rather than structural measures reduce the immediate risk of a breakup in the cited court decision.
Risks
- Regulatory requirements can weaken Alphabet’s integration advantages and the economic efficiency of the advertising business.
- Further fines, appeals, and regulatory decisions can trigger additional volatility.
- High expectations for Gemini and Google Cloud increase the risk of disappointment.
- Analyst price targets may only belatedly account for changes in interest rates, investment assumptions, or competition in the AI sector.
Key takeaway: Strong results, increasing use of artificial intelligence, and broad buy consensus outweigh regulatory burdens and support a positive assessment of news and market sentiment.
MUMAK.me Valuation Phase 4: Positive = 1 MUMAK
Alphabet Inc.
Technical Analysis
Classification
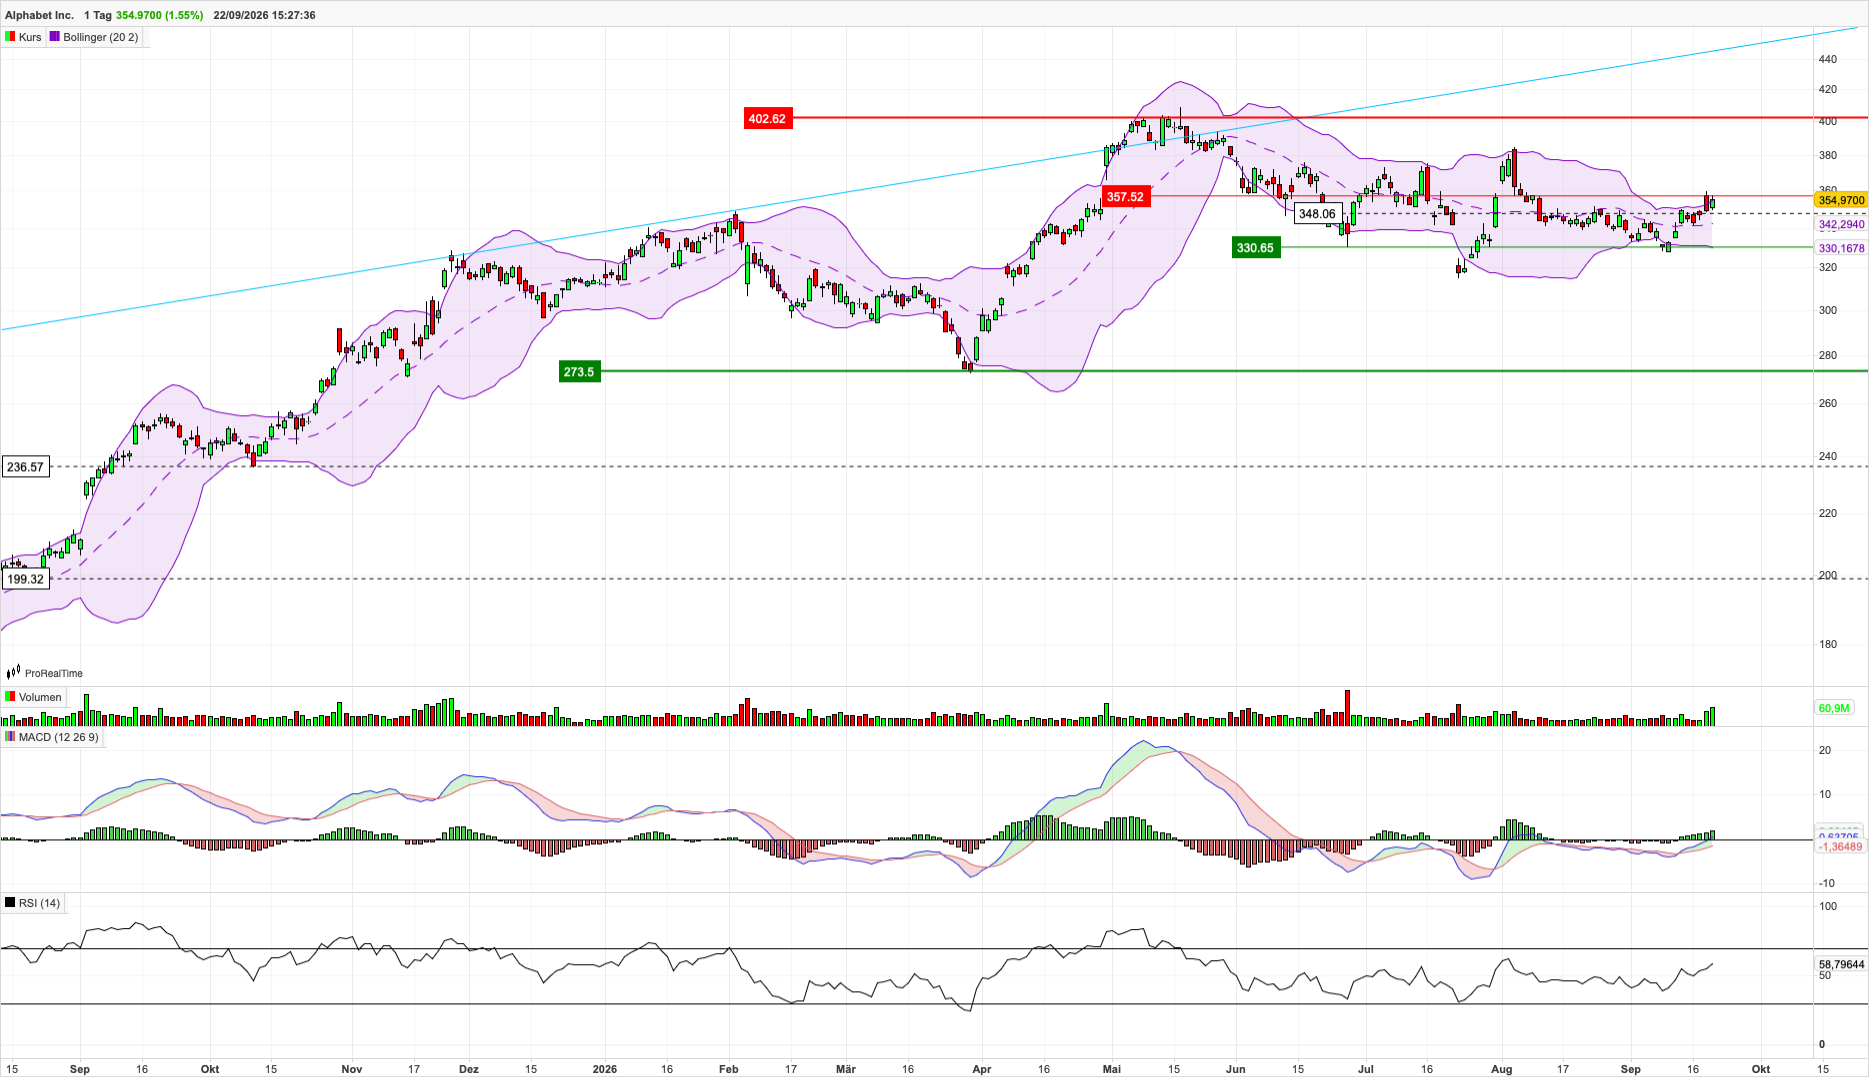
Alphabet A-shares closed at $349.54 on September 18, 2026. On September 14, the stock opened at $343.12, slightly above the previous trading day’s high of $342.98. This created an upward gap after a period of narrowing Bollinger Bands.
The session ended with a price gain of 3.2%. In the following week, the stock continued to trade above the midline of the Bollinger Bands.
The RSI (14) was around 57 on September 18, signaling constructive momentum without indicating an overbought condition. The MACD line remained close to the neutral zone but was significantly above its signal line. This indicated increasingly positive momentum.
After an interim high of $359.44, the stock closed below the upper Bollinger Band at around $352.50. An initial support zone was in the breakout area at $342–343. Below that, further support was located at around $331–333.
Development in Recent Weeks/Months
Technical indicators
| Indicator | Assessment | Interpretation |
|---|---|---|
| RSI (14) | Positive | Around 57; positive momentum without an overbought signal |
| MACD | Positive | MACD momentum near the neutral zone, with the MACD line above its signal line |
| Bollinger Bands | Positive | Price above the midline and near the upper Bollinger Band |
Opportunities
- A price above $342–343 would confirm the breakout structure.
- A sustained rise above $359–360 could confirm a renewed upward movement.
- The RSI allows further room for price increases before an overbought area is reached.
- Increasing MACD momentum supports the positive short-term signal.
Risks
- The price reversal from the daily high of $359.44 on September 18 indicates a resistance area at $359–360.
- A close below $342 could close the upward gap and weaken the breakout.
- A drop below $331–333 would significantly worsen the short-term technical chart picture.
- At the time of inclusion in the UMBRELLA Strategy, no binding stop-loss level had yet been set.
Key takeaway: The upward gap after the narrowing of the Bollinger Bands, the positive RSI, and improving MACD momentum support a positive technical chart valuation. However, risk management requires setting a binding stop-loss level.
MUMAK.me Valuation Phase 5: Positive = 1 MUMAK
Alphabet Inc.
What currently favors Alphabet?
- Revenue and operating income are growing significantly.
- Google Cloud is experiencing accelerated growth and increasing its earnings contribution.
- Alphabet combines AI models, proprietary chips, infrastructure, and a global sales reach.
- The analyst consensus is “Buy”, and the average price target signals further upside potential.
- The September breakout followed a narrowing of the Bollinger Bands and was accompanied by higher trading volume.
- The group has extensive liquidity reserves and strong operating cash flow.
What currently argues against Alphabet?
- High investments in AI infrastructure put significant pressure on free cash flow.
- Regulatory measures in the USA and EU can impair the integration and monetization of key platform offerings.
- Competition in AI, cloud, internet search, and digital advertising is intense.
- The reported earnings for 2026 are distorted by high unrealized gains from equity investments.
- At the time of inclusion, the binding stop-loss level had not yet been set.
What we are observing
- The development of revenue, operating margin, and Google Cloud in the third quarter of 2026.
- Capital expenditures, operating cash flow, and the further development of free cash flow.
- The adoption of Gemini, AI-powered use of Google Search, and monetization of the advertising business.
- The implementation and financial impact of US requirements for the ad tech business and EU DMA decisions.
- The final determination and subsequent monitoring of the binding stop-loss level.
Summary
Alphabet was included in the UMBRELLA Strategy with a consistent fundamental and technical signal. The group combines strong revenue growth, increasing operating profitability, the dynamic development of Google Cloud, and a broad buy consensus among analysts. The upward gap after the narrowing of the Bollinger Bands additionally confirmed the positive entry signal.
The main risks are also clearly identifiable. High investments in AI infrastructure burden free cash flow, regulatory measures change the economic framework for important platform businesses, and competition remains intense.
The further development of the position therefore depends on continuously strong operational execution and disciplined risk management. This includes, in particular, setting a binding stop-loss level.
Rating According to the MUMAK Method
| Category | Rating |
|---|---|
| Geopolitics | Positive |
| Industry | Positive |
| Fundamentals | Positive |
| News & Sentiment | Positive |
| Technical Analysis | Positive |
Overall Rating


