
Micron Technology: Record Quarter Thanks to AI and Data Centers
Micron Technology (NASDAQ: MU) reported record results for the fourth quarter of fiscal year 2026, confirming the strong fundamental development that had supported the company’s inclusion in the UMBRELLA Strategy in September.
Revenue reached $54.23 billion, up from $41.46 billion in the previous quarter and $11.32 billion in the fourth quarter of 2025. Non-GAAP net income rose to $38.40 billion, corresponding to diluted non-GAAP earnings per share of $33.42. Operating cash flow reached $43.97 billion.
The results were also above the outlook that formed the basis of our valuation analysis from September. Micron had previously forecast Q4 revenue of approximately $50 billion and EPS of $30.73. Actual results were $54.23 billion in revenue and $33.42 in EPS.
Q4 2026 at a Glance
| Key Figure | Q4 2026 | Q3 2026 | Q4 2025 |
|---|---|---|---|
| Revenue | $54.23 billion | $41.46 billion | $11.32 billion |
| GAAP Net Income | $37.70 billion | $28.24 billion | $3.20 billion |
| GAAP EPS | $32.87 | $24.67 | $2.83 |
| Operating Cash Flow | $43.97 billion | $25.39 billion | $5.73 billion |
Source: Micron Technology, Fourth Quarter Fiscal Year 2026 Results.
Key Highlights
Record quarterly revenue of $54.23 billion, representing another significant sequential acceleration.
Non-GAAP gross margin reached 87.0%, up from 84.9% in Q3.
Revenue in the Core Data Center segment increased to $18.0 billion from $11.52 billion in the previous quarter.
Cloud Memory generated revenue of $16.28 billion.
Adjusted free cash flow reached $33.20 billion in the quarter.
Micron ended fiscal year 2026 with $73.48 billion in cash, marketable securities, and restricted cash.
Management expects the positive momentum to continue into fiscal year 2027.
What defined the quarter?
The central growth driver remains Artificial Intelligence and the rapid expansion of data center infrastructure.
Micron’s Core Data Center Business Unit generated revenue of $18.0 billion, compared to $11.52 billion in the third quarter and only $1.58 billion in the corresponding prior-year quarter. The Cloud Memory segment also continued to perform strongly with revenue of $16.28 billion.
This development confirms one of the central assumptions of our original Micron analysis: memory-intensive AI applications create structural demand for high-performance DRAM, HBM, and data center memory solutions. Our September analysis identified AI infrastructure, HBM, and rising memory prices as key drivers for Micron’s improved fundamental development.
At the product level, development also remains supportive. Micron reported further customer qualifications for its latest server memory products and strong sequential growth in the SOCAMM business.
Strong Outlook for Q1 2027
Management expects the positive momentum to continue at the start of the new fiscal year.
For the first quarter of fiscal year 2027, Micron forecasts:
| Key Figure | GAAP Forecast Q1 2027 |
|---|---|
| Revenue | $61.5 billion ± $1.5 billion |
| Diluted EPS | $37.84 ± $1.00 |
Based on the midpoint, the revenue outlook corresponds to a further sequential increase of approximately 13% compared to Q4. The forecast thus indicates that Micron expects strong AI-related memory demand and a favorable market environment for memory chips to continue in fiscal year 2027.
Technical Analysis: Micron Approaches Key Resistance Zone
The technical picture has also continued to improve since our valuation analysis in early September.
At that time, Micron was trading at approximately $1,016. We had identified the area around $1,080 as the next important resistance, followed by the previous high of approximately $1,210.
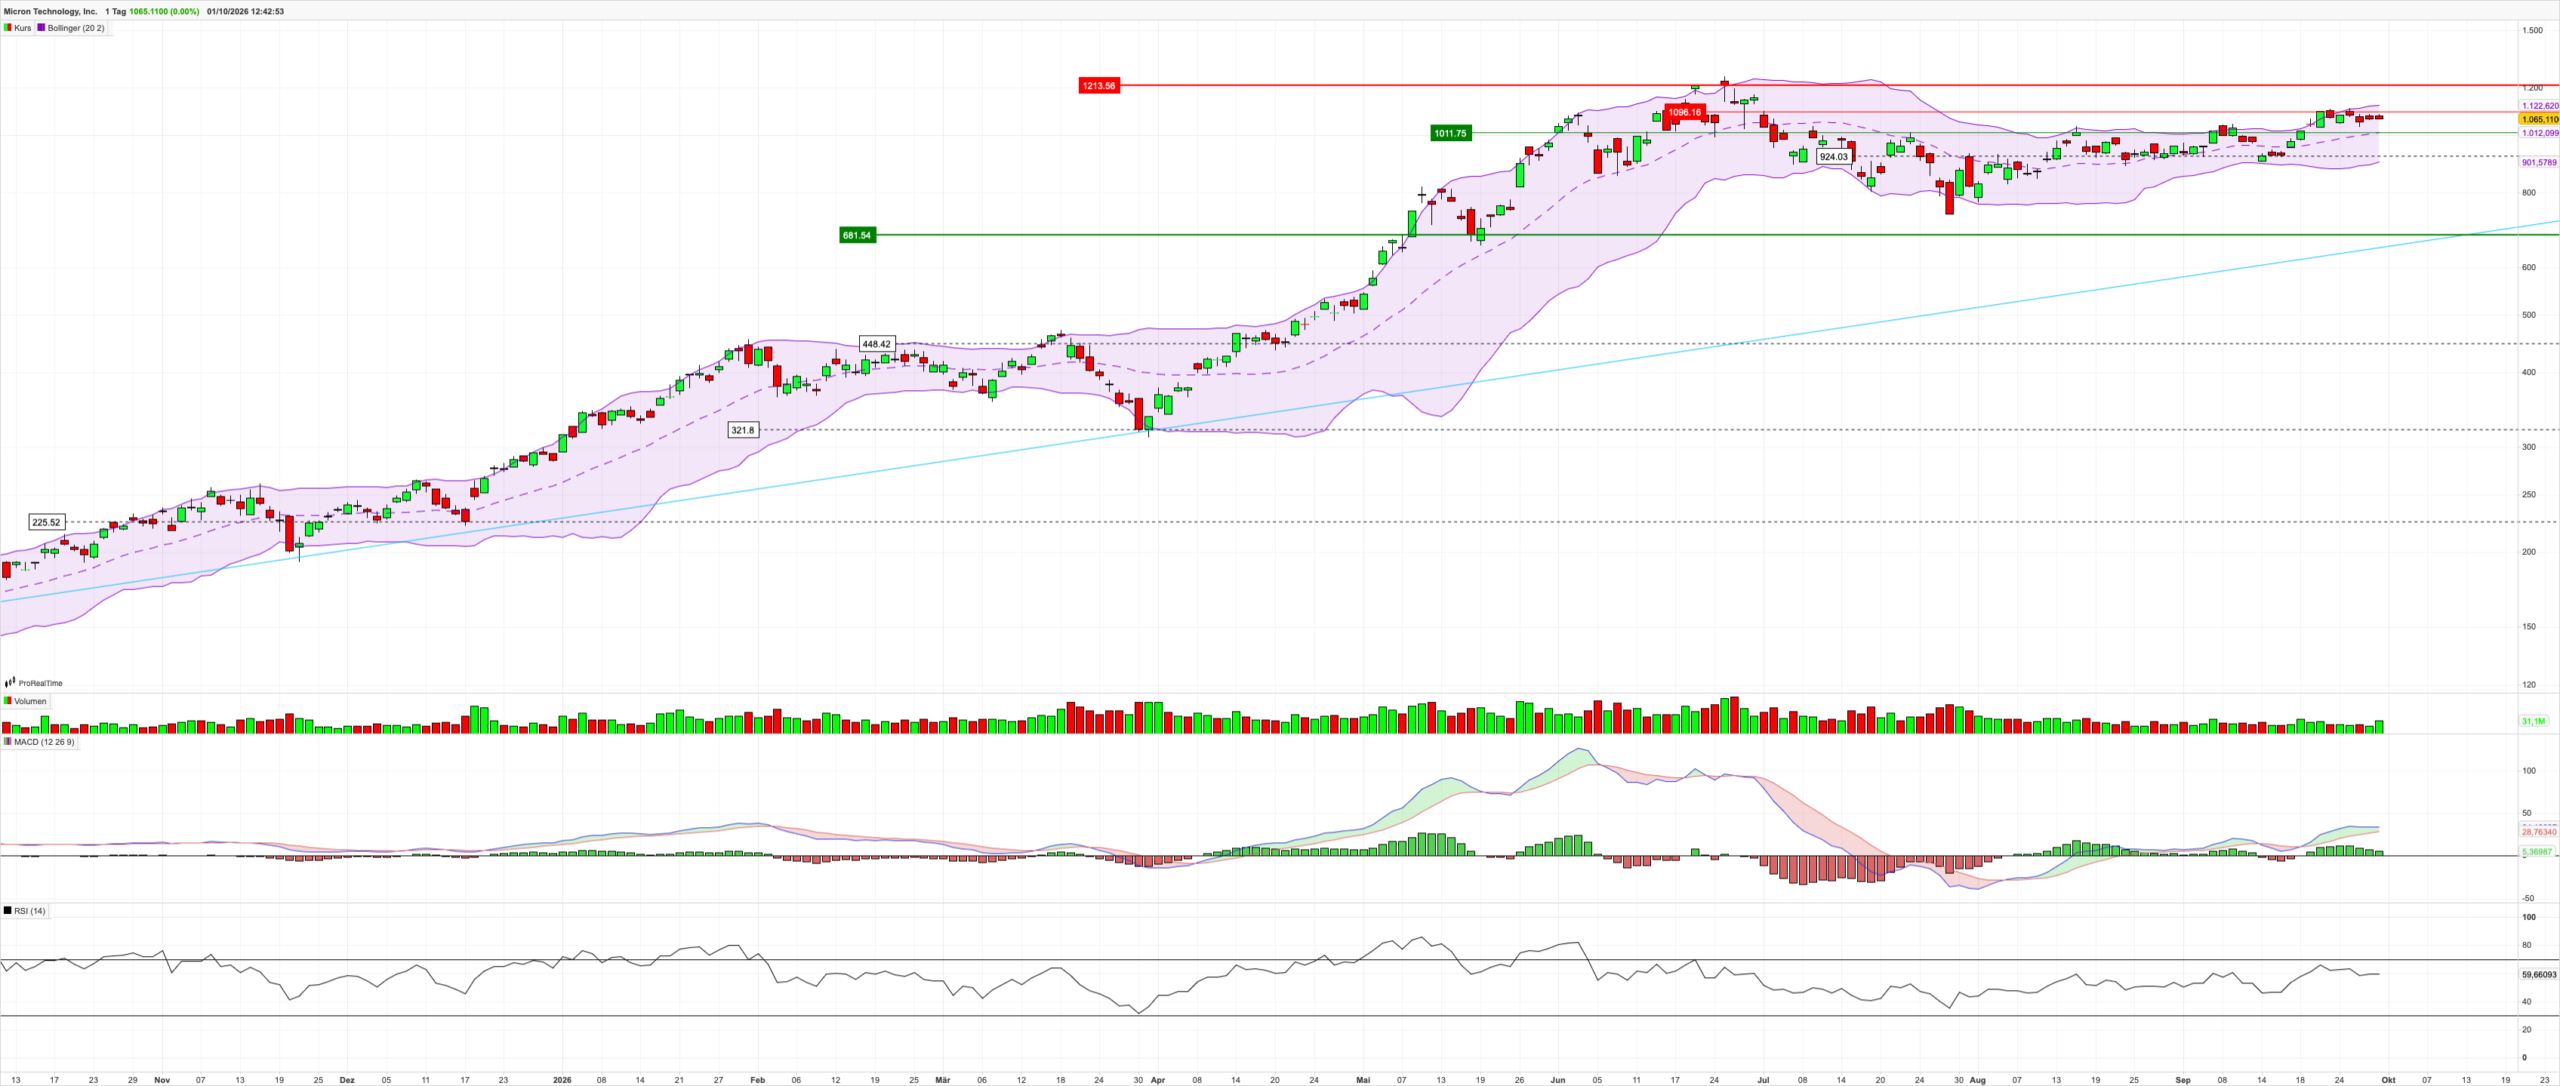
The current chart shows that Micron has now clearly surpassed the $1,080 area and is trading at approximately $1,122. The stock thus remains above the middle Bollinger Band and is approaching the former high or resistance zone at about $1,210–$1,214.
The MACD remains positive, with the MACD line continuing to run above the signal line. The RSI is around 60, still signaling positive momentum.
MUMAK Assessment
Micron’s Q4 results strengthen the overall fundamental picture that supported the company’s inclusion in the UMBRELLA Strategy.
Particularly relevant is the combination of record revenue, very high profitability, strong cash flow generation, and continuously growing demand for data center memory solutions. Furthermore, both revenue and earnings exceeded the forecast values that formed the basis of our September valuation analysis.
The outlook for the first quarter of 2027 also provides another positive fundamental signal. Management expects a further revenue increase to approximately $61.5 billion.
From a technical analysis perspective, the development has also continued positively since our original analysis. The previously identified resistance at approximately $1,080 has been overcome, while the stock is now approaching the $1,210–$1,214 range.
Risks nevertheless remain. Memory markets are cyclical, current profitability is at an exceptionally high level, expectations have risen significantly, and the expansion of production capacities requires considerable investment. These factors remain relevant as we transition into fiscal year 2027.
Conclusion
Micron’s record results for Q4 2026 provide fundamental confirmation of the AI and data center memory thesis that underpins the company’s inclusion in the UMBRELLA Strategy.
Revenue and earnings surpassed the company’s previous Q4 outlook, while the forecast for the first quarter of 2027 points to further growth. At the same time, the technical chart picture remains positive after breaking above the previously identified resistance at $1,080.
