Strategic realignment: Healthcare sector gains significance, technology risks are reduced
The past trading week was characterized by significant fluctuations on the US stock exchanges and an intensive quarterly earnings season. Technology and AI companies in particular came under pressure, while selected healthcare companies attracted attention with convincing business figures.
On Friday, October 30, the Nasdaq Composite lost 2.86%, while the S&P 500 gave up 1.82%. Investors increasingly questioned the high capital expenditures of technology groups and their future profitability.
The US Federal Reserve left the key interest rate unchanged at 3.75–4.00% on October 28. At the same time, geopolitical developments and the upcoming US midterm elections are causing additional uncertainty.
The UMBRELLA Strategy reacted with targeted portfolio adjustments. The focus was on the readmission and increase of Bayer, as well as significant reductions in Alphabet and SpaceX.
Our focus remains the combination of healthcare, artificial intelligence, aerospace technology, and defense.
Portfolio changes at a glance
The adjustments reflect our active investment approach. While the legal situation for Bayer improved, we reacted to increased technical risks at Alphabet and SpaceX.
Bayer: Legal breakthrough supports readmission
One of the most important decisions was the readmission of Bayer into the UMBRELLA Strategy.
On October 29, a jury in Missouri decided unanimously in favor of the Bayer subsidiary Monsanto. This was the first Roundup trial following the landmark decision by the US Supreme Court in June 2026.
The plaintiffs were unable to prevail with their allegations regarding product defects, deception, and negligence.
This success significantly improves the legal starting position in the glyphosate litigation complex. However, further proceedings and financial risks persist. The final approval of the broader settlement also remains to be seen.
Together with the positive technical development, this supported our decision to readmit Bayer and subsequently increase the position significantly.
The stock is now weighted at 7.2% in the portfolio.
Alphabet and SpaceX: Consistent risk reduction
At Alphabet, the quarterly figures from October 28 were the focus.
The group reported revenue growth of 25% to USD 127.6 billion. Google Cloud developed particularly impressively with growth of 103% to USD 30.7 billion.
Despite this strong operational development, the stock market reacted negatively. In particular, the significant investments in AI infrastructure and the question of their future profitability weighed on the valuation.
Due to the negative price reaction and the deteriorated technical starting position, we significantly reduced Alphabet to 4.6%.
The exposure to SpaceX was also scaled back.
Following recent price fluctuations and uncertainties surrounding expiring lock-up periods, we decided on a gradual reduction.
SpaceX remains a significant holding at 10.7%. The long-term growth perspective remains interesting, but in the short term, technical stabilization is the priority.
Lockheed Martin was completely removed from the portfolio, taking existing ESG requirements into account.
Eli Lilly: Outstanding quarterly figures confirm investment thesis
One of the most convincing corporate developments was delivered by Eli Lilly.
The US pharmaceutical group presented exceptionally strong quarterly results on October 29:
- Revenue growth of 39% to USD 24.4 billion
- Adjusted earnings per share of USD 7.48
- Increase in the annual revenue guidance to USD 91–92 billion
The main growth drivers remain the drugs Mounjaro and Zepbound for the treatment of diabetes and obesity.
Increasing global demand, additional production capacities, and the expansion of the product portfolio support the long-term business prospects.
Eli Lilly is currently our largest portfolio position at 18.3% and has shown a positive position performance of around 23% since its inclusion.
AbbVie and Revolution Medicines strengthen the healthcare segment
AbbVie also impressed with its quarterly figures published on October 30.
Revenue rose by 10.3% to USD 17.4 billion. Adjusted earnings per share reached USD 3.82. The drugs Skyrizi and Rinvoq in particular supported the development of the immunology business.
The company also raised its annual profit guidance.
Revolution Medicines also remains one of our most important holdings. The company develops innovative cancer therapies, with the commercial development of RASONQUE and further clinical progress at the center.
With a current weighting of 16.6%, Revolution Medicines is among our largest positions.
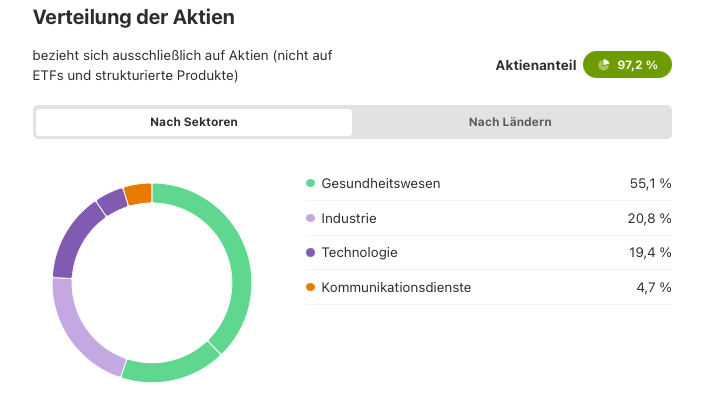
Together with Johnson & Johnson and Bayer, healthcare has now become by far the most important sector focus of our strategy.
Current Sector Distribution
The recent adjustments have significantly changed the sector weighting.