

PayPal Holdings, Inc.
First published: August 26, 2026
Updated: August 28, 2026 | Market data: Intraday August 28, 2026
Due to the shift in market sentiment and the deteriorated technical picture, the MUMAK rating has been adjusted from 4 to 3 out of 5 MUMAKS as part of this update.
PayPal is among the largest global digital payment companies, connecting consumers, merchants, and financial institutions through a broad-based payment ecosystem.
The company operates various platforms and services, including PayPal, Venmo, Braintree, Xoom, and PayPal Open. Its business encompasses online checkout, peer-to-peer payments, merchant payment processing, international money transfers, and increasingly, payment solutions in the field of digital assets.
Unlike traditional banks, PayPal acts primarily as a technology-based intermediary within the global payment infrastructure. The company’s development therefore depends not only on consumption and e-commerce but also on the regulatory environment for digital payments, financial services, data protection, cybersecurity, cryptocurrencies, and cross-border transactions.
In recent years, PayPal has also expanded its engagement in the digital asset space with PayPal USD (PYUSD) and its cryptocurrency services. Consequently, the regulation of this sector is gaining additional importance for the company’s long-term development.
Update from August 28, 2026
Since the initial publication of the analysis on August 26, the news flow regarding PayPal has changed. According to media reports, Stripe and Advent International are no longer pursuing the previously discussed acquisition of PayPal. The consortium had previously offered approximately USD 60.50 per share, or more than USD 53 billion, for the company.
The fundamental assessment of the operating business remains unchanged for now. However, market sentiment and the technical setup seem to have deteriorated and have been re-evaluated accordingly.
Assessment
This analysis assesses PayPal according to the MUMAK UMBRELLA Strategy.
The assessment is carried out across five decision phases: Geopolitics, Industry, Fundamentals, Market Sentiment, and Technical Analysis.
The goal is not to predict the future precisely. The goal is to provide orientation. We classify facts, illustrate their interrelationships, and structure a comprehensible decision-making logic.
We explain – you decide.
Geopolitics
Classification
PayPal is part of a highly globalized payments ecosystem where regulation, international trade, sanctions policy, and financial infrastructure play a crucial role.
Approximately 42% of PayPal’s net revenue in Q1 2026 was generated with customers outside the USA. Thus, the business is significantly influenced by economic and regulatory developments in the USA, Europe, and other key markets.
Concurrently, the long-term geopolitical environment supports the further digitalization of payment systems. Governments and regulators are promoting faster electronic payments and more integrated payment infrastructures. In Europe, the Instant Payments Regulation is progressively expanding the requirements for Euro real-time transfers. Furthermore, a political agreement was reached in November 2025 on the further development of PSD2 within the framework of PSD3 and the Payment Services Regulation.
These developments support the transition from cash to digital financial infrastructure, while simultaneously leading to higher regulatory requirements.
PayPal is subject to comprehensive regulations in the areas of payment services, anti-money laundering, sanctions, consumer protection, cybersecurity, and data protection. Geopolitical tensions are also relevant, as payment service providers must comply with international sanctions regimes.
Another strategically important area is digital currencies. In July 2025, the USA established a federal regulatory framework for stablecoins with the GENIUS Act. This is directly relevant for PayPal due to its own stablecoin PYUSD and its cryptocurrency activities.
Regulation is also evolving in Europe. The European Commission is currently reviewing the implementation of the Markets in Crypto-Assets Regulation (MiCA).
Opportunities
- Digital payments are increasingly replacing cash worldwide.
- E-commerce growth supports payment volume.
- Real-time payments expand the digital payment infrastructure.
- PYUSD offers access to the regulated stablecoin market.
- PayPal benefits from an established global payment network.
Risks
- Financial market regulation is becoming more complex.
- Sanctions and geopolitical tensions can restrict transactions.
- Data protection and cybersecurity rules increase regulatory requirements.
- Cryptocurrency regulation could affect PYUSD and related services.
- International activities create currency and cross-border risks.
Key takeaway: The geopolitical environment for PayPal is supportive, but increasingly regulated.
MUMAK.me Rating Phase 1: Positive = 1 MUMAK
PayPal Holdings, Inc.
Industry
Classification
The industry continues to benefit from structural trends such as the shift from cash to digital payments, e-commerce growth, the increasing use of mobile payments, and rising demand for integrated payment solutions.
PayPal continues to operate on a significant scale. In Q2 2026, the company processed a Total Payment Volume (TPV) of USD 486.4 billion – an increase of 10% year-over-year. A total of approximately 6.8 billion payment transactions were processed.
However, competition is high. PayPal competes with global card networks such as Visa and Mastercard as well as payment service providers and fintech platforms like Block and Adyen.
PayPal in valuation comparison
| Metric | PayPal 2026e | Industry Average* | Valuation |
|---|---|---|---|
| P/E Ratio | 12.3x | approx. 20–35x | Stronger / lower valuation |
| EBIT Margin | 17% | approx. 15–55% | In line |
| Net Margin | 13% | approx. 10–45% | In line |
| Revenue growth | approx. 4–5% | approx. 5–15% | Weaker |
*The peer group includes Visa, Mastercard, Block, Adyen, and Fiserv.
Source: MarketScreener consensus estimates and market data, August 2026.
The comparison highlights PayPal’s current position within the payments industry.
With an expected P/E of around 12x for 2026, PayPal is valued significantly lower than many large payments companies. This valuation discount, however, also reflects the slower expected growth and lower profitability versus higher-margin payment networks such as Visa and Mastercard.
Key takeaway: PayPal operates in a structurally attractive digital payments industry supported by the ongoing shift to electronic and mobile payment methods.
MUMAK.me Phase 2 Rating: Positive = 1 MUMAK
PayPal Holdings, Inc.
Fundamentals
Classification
PayPal’s fundamentals are overall positive. The company combines a profitable business model with strong cash flow generation and a solid financial position.
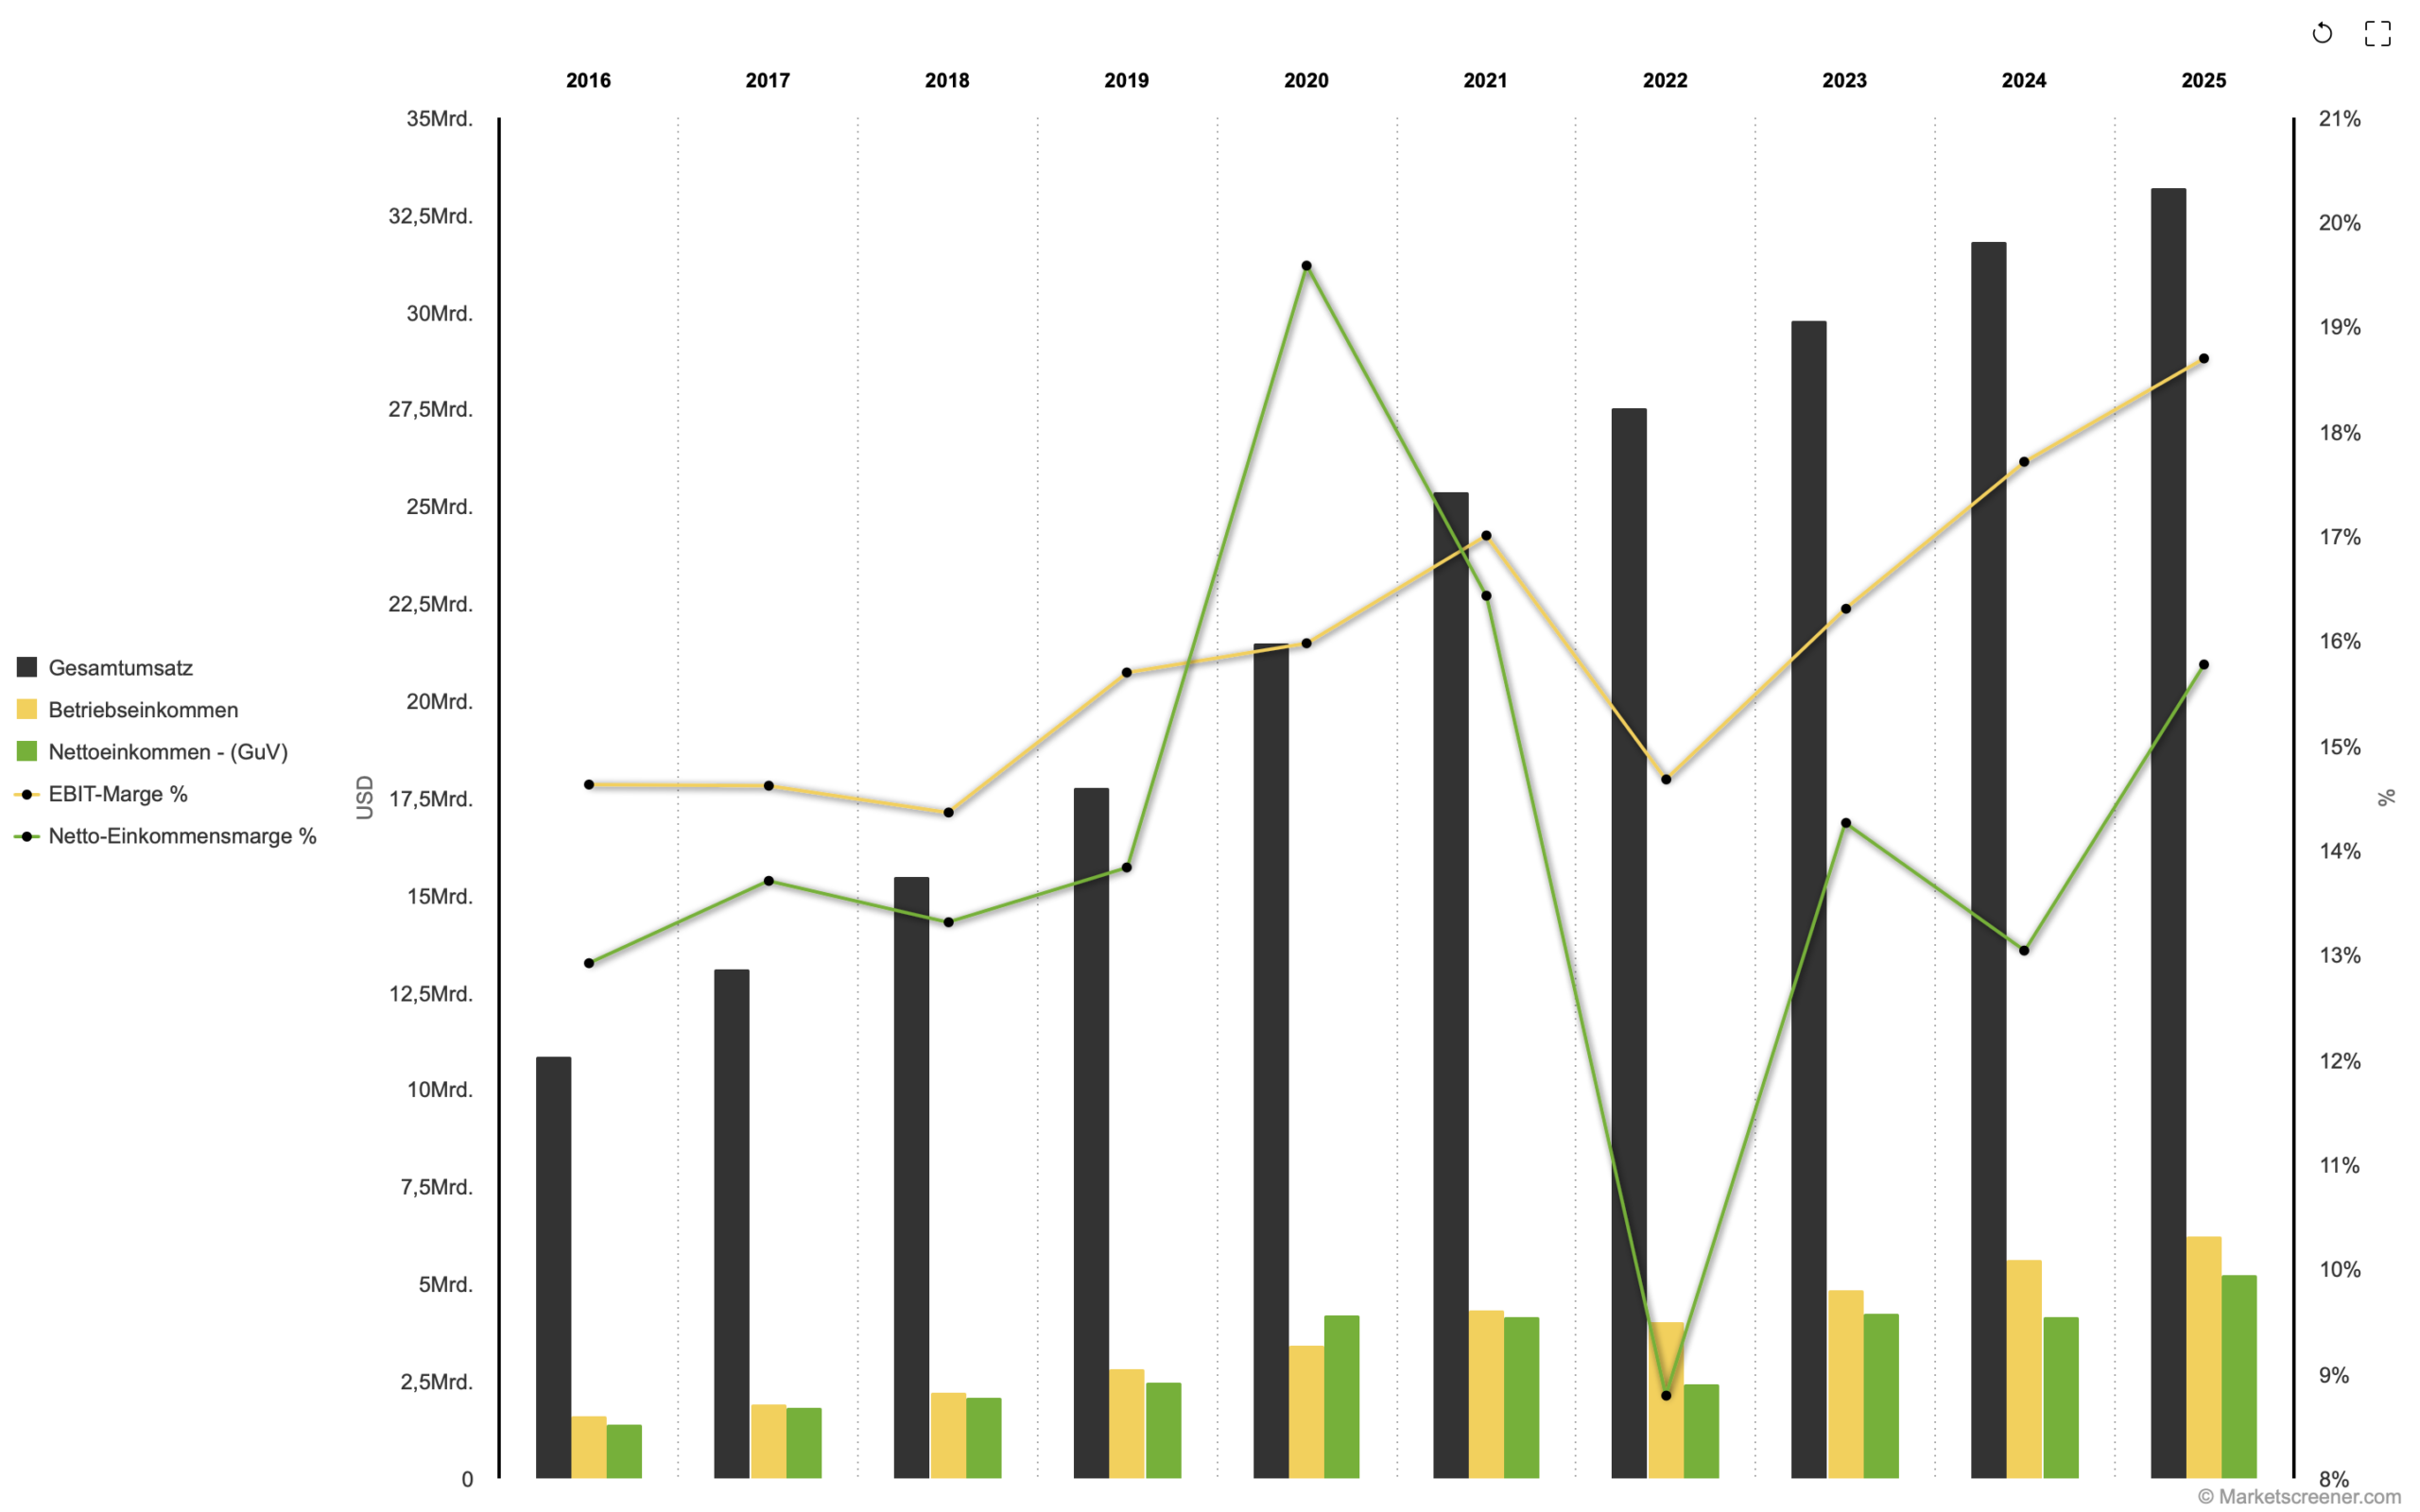
The long-term development also provides a comparatively stable foundation. Revenue rose from around $10.8 billion in 2016 to $33.2 billion in 2025. In fiscal year 2025, PayPal generated revenue of $33.17 billion and net income of $5.23 billion.
The most recent quarterly results, however, also show moderate revenue growth and higher pressure on profitability.
Financial performance
Results for Q2 2026 showed further growth in revenue and payment volume.
| Metric | Q2 2026 | Q2 2025 | Change |
|---|---|---|---|
| Revenue | $8.68 billion | $8.29 billion | +5% |
| Total Payment Volume | $486.4 billion | $443.5 billion | +10% |
| GAAP Operating Income | $1.43 billion | $1.50 billion | −5% |
| GAAP Operating Margin | 16.4% | 18.1% | −1.7 pp |
| GAAP Net Income | $1.10 billion | $1.26 billion | −12% |
| Free Cash Flow | $1.78 billion | $0.69 billion | +157% |
Source: PayPal Q2 2026 Results.
The quarterly figures show two different developments.
On the positive side, payment activity continues to grow. Total Payment Volume increased by 10%, while revenue rose by 5%. At the same time, free cash flow improved significantly to around $1.8 billion.
On the other side, profitability declined year over year. This shows that the higher payment volume is currently not translating proportionally into higher profits.
Long-term financial development
PayPal’s historical financial performance shows a clear long-term increase in revenue. Revenue increased steadily over the past decade and reached around $33.2 billion in 2025.
After high margins in 2020 and 2021, profitability fell sharply in 2022. Since then, PayPal has been able to improve its earnings profile again. Net income rose from $4.15 billion in 2024 to $5.23 billion in 2025.
Outlook 2026–2028
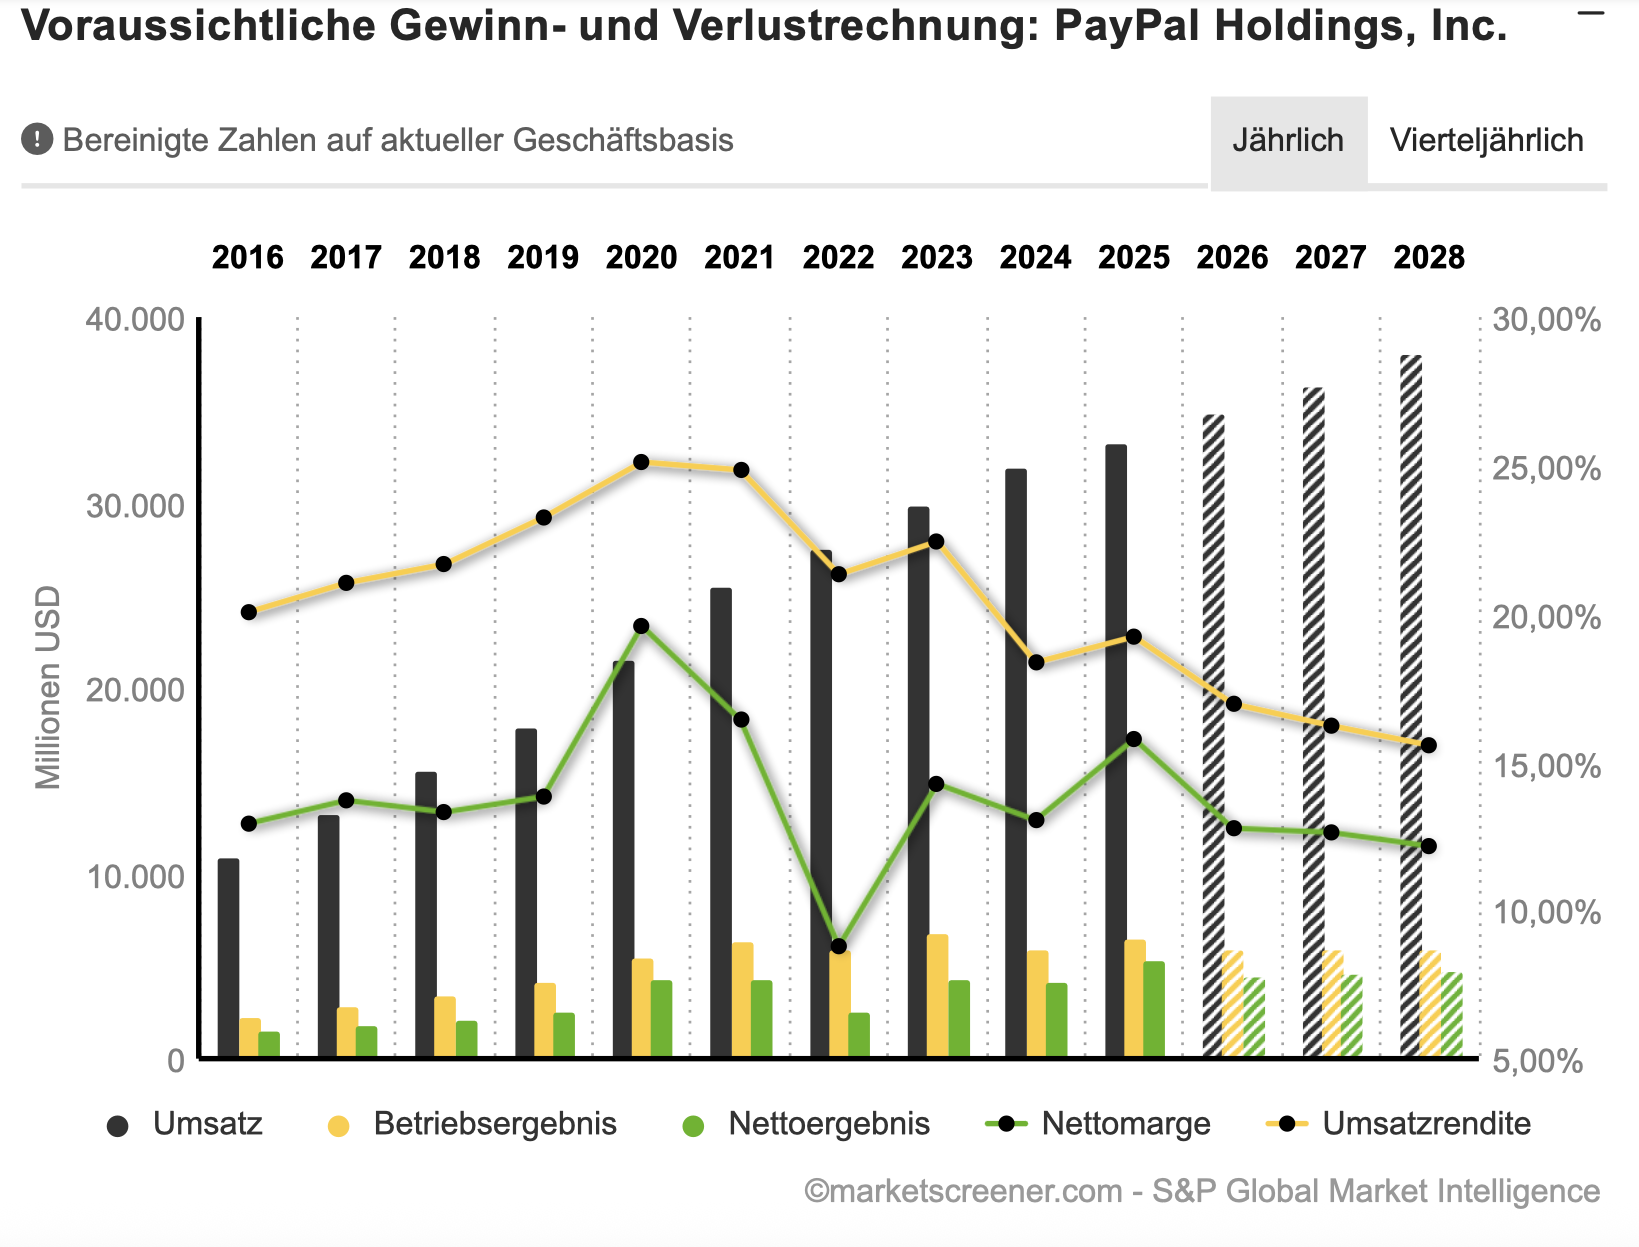
Consensus estimates assume continued, but moderate revenue growth in the coming years.
Source: MarketScreener consensus estimates, August 2026.
The estimates show that revenue could rise from around $33.2 billion in 2025 to $37.9 billion by 2028. Annual growth is expected to be around 4–5%.
The earnings outlook is more cautious. Consensus currently expects EBIT and net income to decline in 2026 before results stabilize in subsequent years.
Cash flow and financial position
Cash flow generation is one of PayPal’s key fundamental strengths.
In Q2 2026, the company generated around $1.8 billion in free cash flow, an increase of 157% versus the prior-year quarter.
The strong cash flow gives PayPal financial flexibility for technology investments, product development, share buybacks, and distributions to shareholders.
Outlook 2026
Following the Q2 2026 results, PayPal raised its full-year guidance for non-GAAP earnings per share.
Management now expects non-GAAP earnings per share of around $5.38 for 2026, up from $5.31 in 2025. At the same time, GAAP earnings per share are still expected to decline in the mid-single-digit percentage range.
Opportunities
- Payment volume continues to grow.
- Strong free cash flow generation.
- The business model remains profitable.
- Revenue is expected to continue growing through 2028.
- High cash flow provides financial flexibility.
Risks
- Revenue growth remains moderate.
- Margins are under pressure.
- Lower results are expected for 2026.
- Competition could weigh on profitability per transaction.
- Higher payment volumes do not automatically translate into higher profits.
Key takeaway: PayPal’s fundamentals are overall positive. The company combines a profitable business model with rising payment volumes and strong cash flow generation, while moderate growth and margin pressure still need to be monitored.
MUMAK.me Rating Phase 3: Positive = 1 MUMAK
PayPal Holdings, Inc.
News, Analysts, and Market Sentiment
Assessment
Short-term market sentiment towards PayPal has deteriorated. This is primarily due to the disappearance of the previously existing acquisition speculation involving Stripe and Advent. This resulted in a strong negative share price reaction.
Operationally, strong free cash flow, increasing payment volumes, and the raised earnings forecast remain supporting factors.
In the second quarter, the company reported revenue growth of 5% and a 10% increase in Total Payment Volume. At the same time, management raised its full-year non-GAAP earnings forecast, citing improved performance in Venmo and Braintree.
Concurrently, PayPal is increasingly expanding its business beyond traditional online checkout.
Analyst Consensus
| Average Recommendation | HOLD |
| Number of Analysts | 43 |
| Average price target | approx. USD 60 |
| Distance to average target | approx. +11% |
| Highest price target | USD 147 |
| Lowest price target | USD 36 |
Source: MarketScreener Consensus, August 2026.
Analyst consensus remains cautious despite recent operational improvements.
Several analysts raised their price targets following the Q2 results. UBS increased the price target from $48 to $61 and affirmed its “Neutral” rating. Argus raised the price target from $65 to $70 with a “Buy” rating. DA Davidson increased its price target from $51 to $62 and also affirmed “Buy”.
Most recently, Piper Sandler raised the price target from $42 to $59 but maintained its “Neutral” rating. Analyst assessments thus continue to diverge significantly.
Market Sentiment
Market sentiment towards PayPal deteriorated in the short term on August 28.
Fundamentally, the announcement initially brings no changes; however, a significant portion of the previously priced-in acquisition speculation was removed from the share price.
Interesting fact
PayPal has long since stopped focusing exclusively on the classic PayPal checkout button.
The company is increasingly positioning its payments infrastructure through Venmo, Braintree, financial services, and new digital commerce models. This broader ecosystem could gain importance as online checkout continues to evolve.
Key takeaway: The news flow and market sentiment around PayPal deteriorated on August 28.
MUMAK.me rating Phase 4: Negative = 0 MUMAK
PayPal Holdings, Inc.
Technical Analysis (August 28, 2026)
Assessment
PayPal’s technical picture has deteriorated following the significant price decline on August 28, 2026.
The stock fell by approximately 11.6% to $54.34 during the day, thereby giving back a substantial portion of the strong recovery since July. The trigger is the disappearance of the recently priced-in takeover speculation surrounding Stripe and Advent.
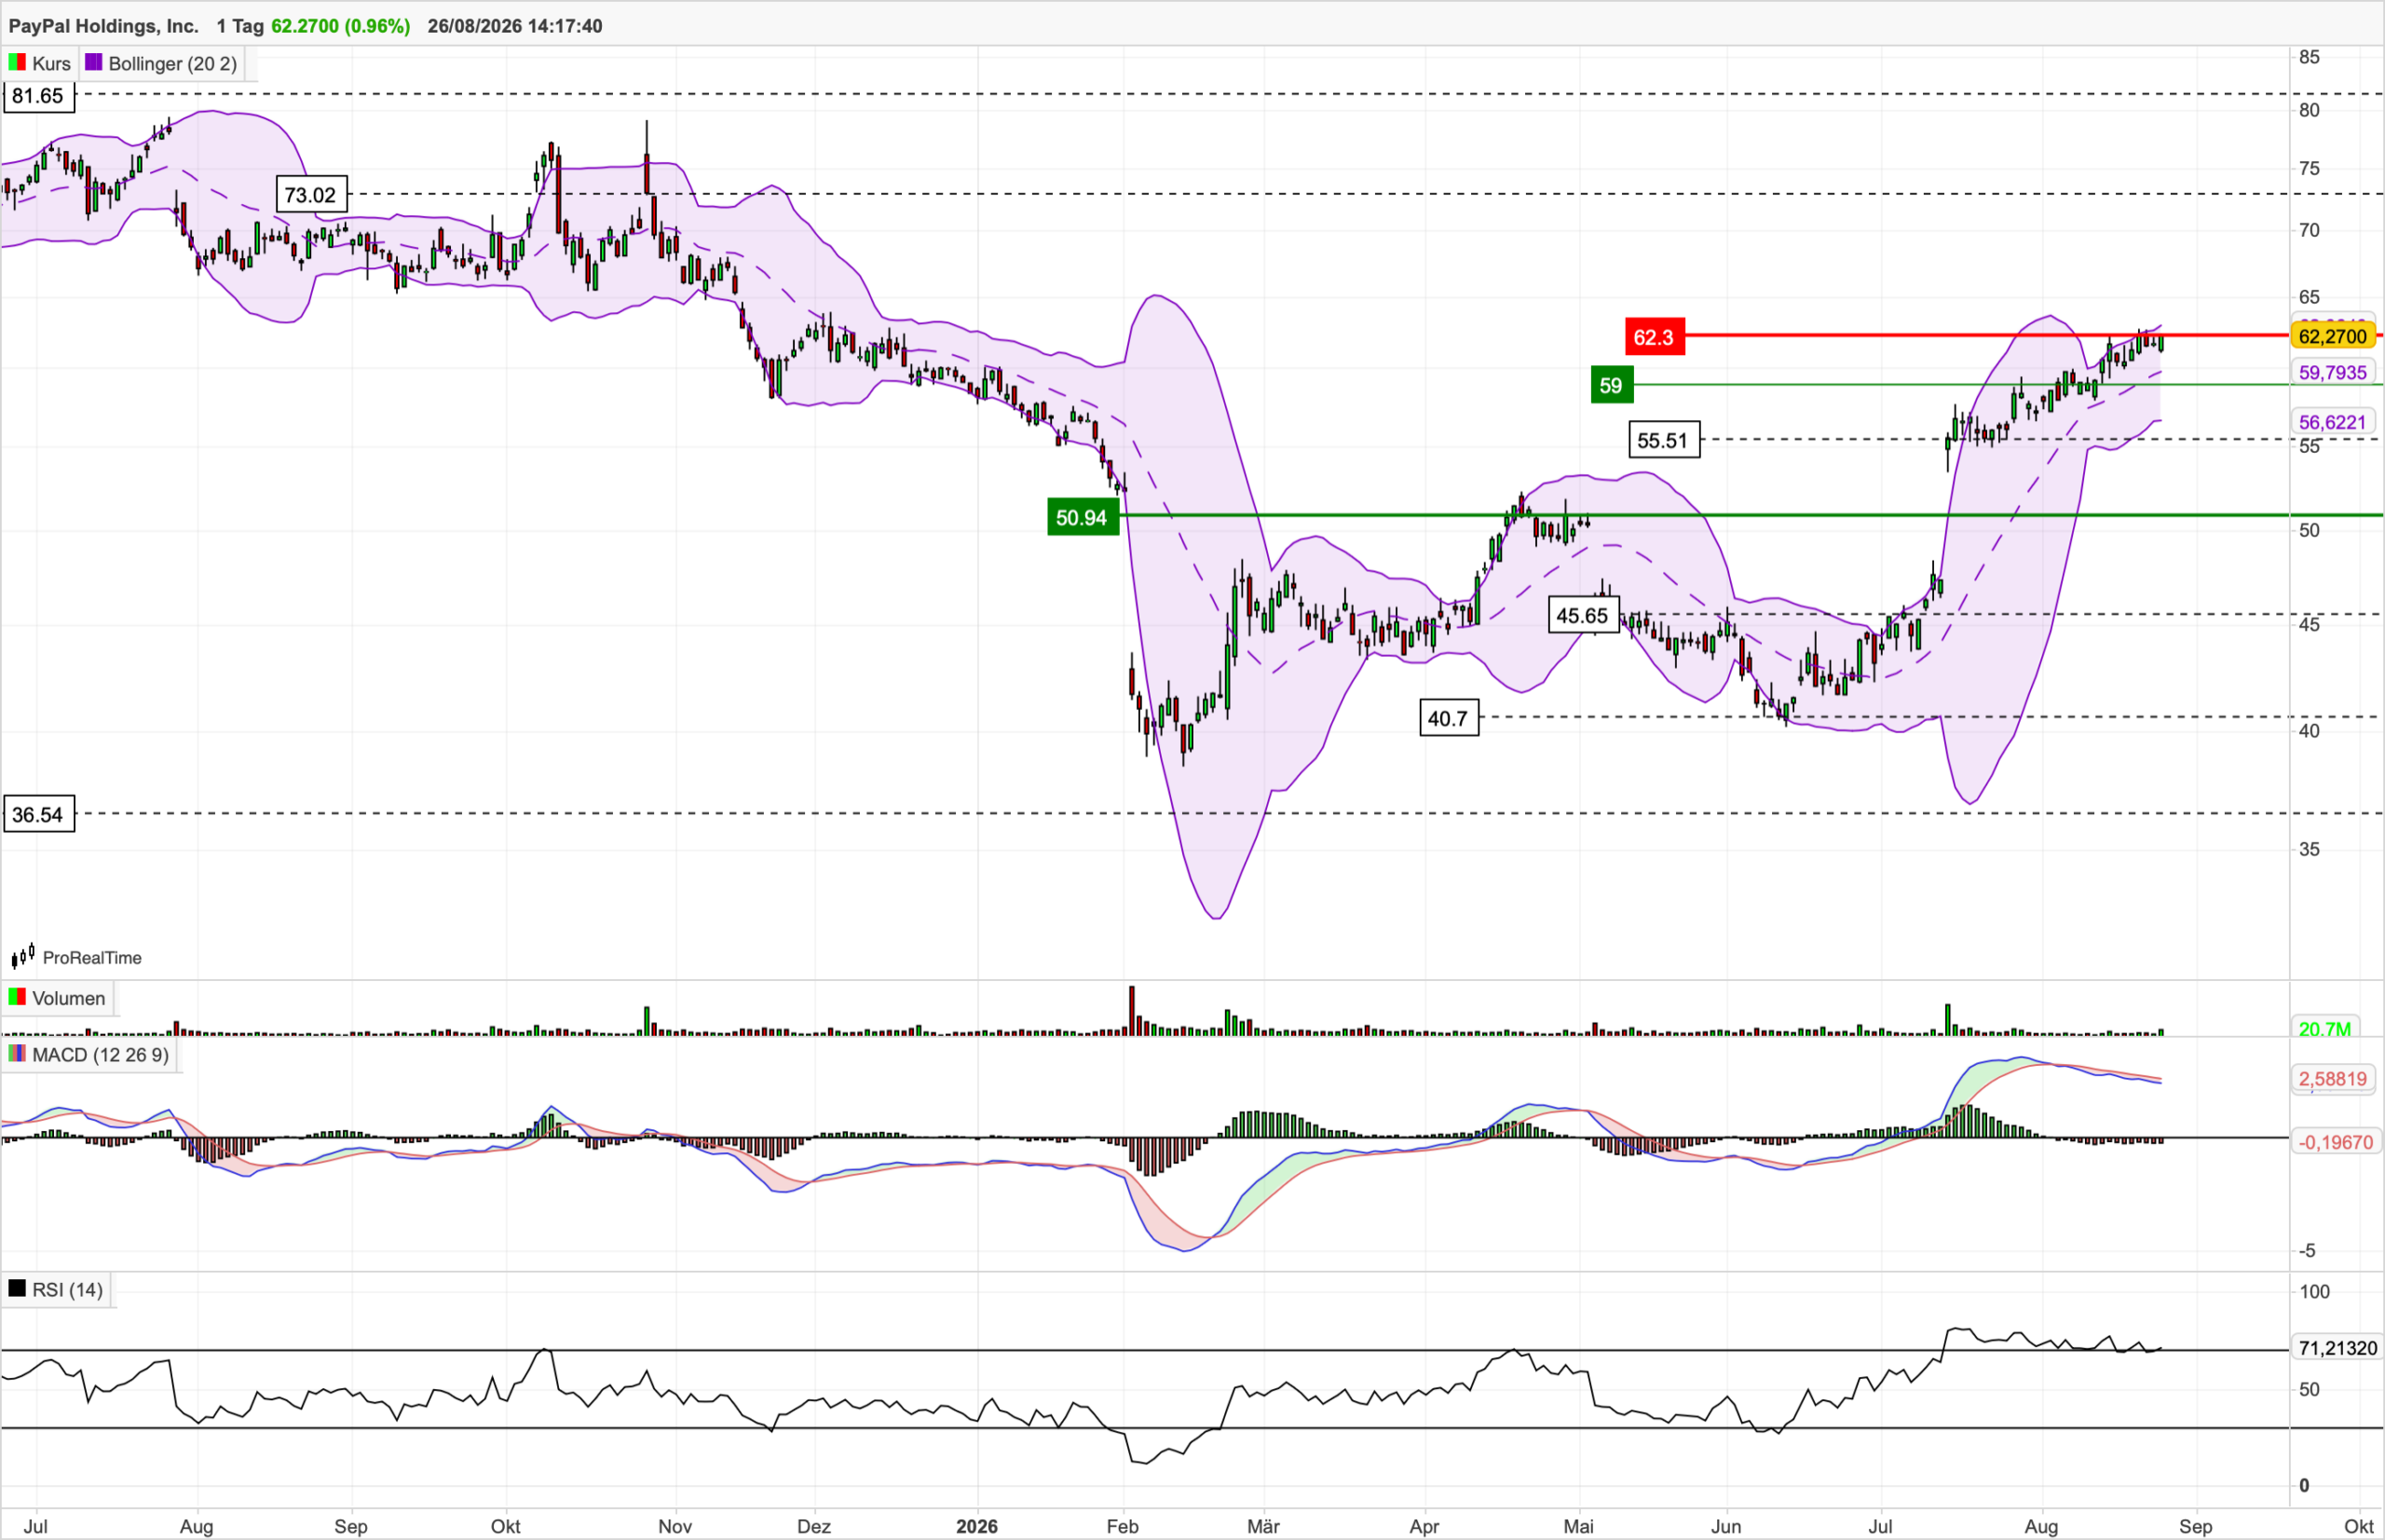
It is particularly relevant that PayPal has once again fallen below the previously overcome support levels at $59.00 and $55.51. Concurrently, the short-term uptrend has been broken. The next significant technical support zone is now in the range of $50.94.
Development over the past weeks/months
(As of: August 28, 2026)
| Indicator | Rating | Interpretation |
| RSI (14) | Neutral/Negative | The RSI has fallen to approximately 36.5. The previously overbought level has been fully unwound. The stock is approaching an oversold situation, but has not yet reached the classic 30 mark. |
| MACD | Negative | The MACD line has fallen significantly below the signal line. |
| Bollinger Bands | Neutral/Negative | At approximately $54.34, the stock is even trading below the lower Bollinger Band of about $56.20. This confirms strong selling pressure, but at the same time signals a short-term technically overextended movement. |
RSI (14)
Neutral/Negative
- The RSI is currently around 36.5.
- Only a few days ago, the indicator was in overbought territory at over 70.
- The sharp price decline has completely reversed the momentum within a very short time.
- A technically oversold condition below 30 has not yet been reached.
Interpretation
The RSI confirms the significant deterioration in short-term momentum. At the same time, a substantial portion of the previous overheating has now dissipated.
MACD (12/26/9)
Negative
- The MACD line is now significantly below the signal line.
- The MACD is negative.
Interpretation
The MACD indicates a shift in momentum. The broader recovery of recent months has not yet been completely negated, but negative signals dominate in the short term.
Bollinger Bands (20)
Neutral/Negative
- Upper Bollinger Band: approx. $63.83
- Middle Bollinger Band: approx. $60.01
- Lower Bollinger Band: approx. $56.20
- Current Price: approx. $54.34
The stock has thus fallen significantly below the lower Bollinger Band.
Interpretation
The break of the lower Bollinger Band illustrates the exceptional strength of the current selling pressure. At the same time, such movements are often overextended in the short term.
Key Technical Levels
On the downside, the zone around $52.70 first comes into focus. This level represented the current intraday low during the dynamic move on August 28.
Should there be a sustained break below this level as well, the next significant support levels, in our view, lie at approximately $45.65 and subsequently $40.70.
On the upside, $55.51 and then $59.00 must first be reclaimed. Only a sustained return above the $59–$60 range would significantly stabilize the technical outlook again. Above that, the next major resistance zone is located at $62.30–$63.80.
Opportunities
- The sharp decline has completely dissipated the previously overbought condition.
- The price is already below the lower Bollinger Band, making the move technically overextended in the short term.
- A quick reclamation of $55.51 could support a technical counter-movement.
Risks
- The support levels at $59.00 and $55.51 were clearly breached.
- The short-term uptrend has been broken.
- The MACD provides a negative momentum signal.
- A break of $52.70 could trigger further downward pressure toward $45.65.
- The high momentum of the price decline suggests significantly increased volatility in the short term.
Key Takeaway: PayPal’s technical outlook has deteriorated following the sharp price decline. The previous breakout above $59 was negated and the short-term uptrend was broken. However, with an RSI of around 36 and a price below the lower Bollinger Band, the move is already considerably overextended.
MUMAK.me Assessment Phase 5: Negative = 0 MUMAK
PayPal Holdings, Inc.
What speaks in favor of PayPal?
- PayPal operates in a structurally growing digital payments market.
- Revenue and Total Payment Volume continue to grow.
- The company generates strong free cash flow.
- Venmo and Braintree offer additional growth opportunities.
- Branded Checkout is showing signs of stabilization.
- After Q2, management raised its 2026 non-GAAP earnings guidance.
- PayPal continues to have a profitable, cashflow-strong business model.
What speaks against PayPal?
- Revenue growth remains moderate compared to faster-growing fintech companies.
- Operating margins are under pressure.
- Competition in digital payments and checkout remains high.
- Higher payment volumes do not automatically lead to higher profits.
- Loss of takeover speculation.
- Deterioration of the chart pattern.
What we are observing
- The development of Branded Checkout and whether stabilization continues.
- Growth and monetization of Venmo and Braintree.
- The development of transaction margins and operating profitability.
- The Q3 2026 results on October 27, 2026 as the next important financial update.
Summary
PayPal is transitioning from an established online payments platform to a broader ecosystem for digital payments and financial services.
The fundamental base is positive. PayPal is profitable, generates strong free cash flow, and continues to grow its payment volume. The Q2 2026 results provided further signals to that effect.
At the same time, the transformation is not yet complete. Revenue growth remains moderate, while margins are under pressure.
From an industry perspective, the long-term shift toward digital and mobile payments continues to provide a supportive backdrop.
Due to the shift in market sentiment and the deteriorated technical picture, the MUMAK rating was adjusted in this update on August 28, 2026, from 4 to 3 out of 5 MUMAKS.
Rating According to the MUMAK Method
| Category | Assessment |
|---|---|
| Geopolitics | Positive |
| Industry | Positive |
| Fundamentals | Positive |
| News & Sentiment | Negative |
| Technical analysis | Negative |
Overall Rating


