Space Exploration Technologies Corp. — SpaceX
SpaceX has evolved far beyond its original role as a rocket manufacturer. Today, the company operates an exceptionally tightly integrated technology platform that links launch infrastructure, satellites, global telecommunications, and artificial intelligence.
SpaceX’s vertically integrated business model further strengthens this position. The company controls a large part of the value chain in-house:
Rocket → Launch → Satellite → Constellation → Ground infrastructure → Connectivity service
The financial structure of the business model is particularly interesting because the company’s most visible activity—the launch of rockets—is no longer necessarily the most important economic growth driver.
Starlink has become the central profit driver.
Starlink is developing into a highly profitable global communications platform, while SpaceX uses this strong position to finance extremely capital-intensive investments in Starship and artificial intelligence.
Rating
This analysis evaluates SpaceX under the UMBRELLA strategy using the MUMAK method.
The valuation is conducted across five decision-making phases: Geopolitics, Industry, Fundamentals, Market Sentiment, and Technical Analysis.
The goal is not to predict the future precisely. The goal is orientation. We contextualize facts, demonstrate causal relationships, and structure a comprehensible decision logic.
We explain – you decide.
Geopolitics
Classification
SpaceX has become of strategic importance to the United States. The company’s role goes far beyond commercial rocket launches. NASA and the U.S. Department of Defense are among its most important customers, while Starshield provides secure satellite-based services for national security applications.
Starlink also has significant geopolitical relevance. Satellite networks can provide communications links when terrestrial infrastructure is unavailable or damaged. At the same time, Europe and other regions are developing their own independent satellite systems to reduce their dependence on U.S. providers.
Opportunities
- Higher defense spending: Rising investment in military space systems.
- Growth of Starshield: Increasing demand for secure satellite-based services.
- Government contracts: Strong demand from NASA and U.S. defense agencies.
- Global connectivity: More and more countries require satellite-based communications solutions.
- Strategic position: SpaceX plays an important role in U.S. access to space.
Risks
- Dependence on government contracts: Public-sector contracts remain an important part of the business.
- Political risk: Government priorities can change.
- Regulation: Permits for rocket launches and spectrum use can delay expansion.
- European competition: Europe is developing its own independent satellite systems.
- Geopolitical restrictions: Some markets could restrict access to Starlink.
Key takeaway: SpaceX benefits from its strategic importance to the U.S. and growing demand for satellite infrastructure. At the same time, political and regulatory risks remain.
MUMAK.me Rating Phase 1: Positive = 1 MUMAK
Space Exploration Technologies Corp. — SpaceX
Industry
Assessment
The global space industry is growing rapidly. Demand for satellite communications, commercial rocket launches, defense systems, and Earth observation continues to rise.
SpaceX holds a strong position in two major markets. Falcon 9 is among the most frequently used orbital launch vehicles worldwide, while Starlink has built a large global satellite network. This combination gives SpaceX a meaningful cost and scale advantage.
The next major development step is Starship. If successfully executed, Starship could significantly increase payload capacity while reducing launch costs at the same time.
However, competition in SpaceX’s markets is intensifying. Blue Origin and Rocket Lab compete in launch services, while Amazon Leo competes with Starlink in the satellite broadband market.
Valuation Comparison
A meaningful historical valuation comparison is currently only possible to a limited extent. SpaceX has only recently gone public, meaning there is not yet sufficient trading and financial history for a reliable comparison with established aerospace and defense companies.
In addition, SpaceX combines launch services, satellite communications, defense activities, and other space technologies within a single company. This makes a direct comparison with traditional aerospace companies difficult.
Opportunities
- Growing space market: Demand for rocket launches and satellites is rising.
- Starlink expansion: Additional customers and markets can be unlocked.
- Starship: Could significantly reduce launch costs.
- Vertical integration: SpaceX controls rockets, satellites, and services.
- High barriers to entry: Space technology requires substantial investment and specialized know-how.
- Military space: Demand from the defense sector is increasing.
Risks
- Intensifying competition: New providers of rocket launches and satellite services are expanding.
- Delays with Starship: Development remains technically demanding.
- High investment requirements: Expansion requires substantial capital.
- Competition in satellite networks: Competing LEO networks are growing.
- Technology risk: Technical failures can delay key programs.
Key takeaway: SpaceX has a strong competitive position in rocket launches and satellite communications. Starship could further extend this advantage, provided development is successful.
MUMAK.me Assessment Phase 2: Positive = 1 MUMAK
Space Exploration Technologies Corp. — SpaceX
Fundamentals
Assessment
SpaceX is now publishing financial information as a listed company, giving investors a much clearer view of the company’s financial trajectory.
The preliminary picture is extraordinary: Very high growth and rapidly improving operating profitability go hand in hand with enormous capital expenditures.
Financial performance
SpaceX is showing very strong growth. In Q2 2026, revenue reached around USD 7.8 bn, representing an increase of 92% year-on-year.
Adjusted EBITDA rose to around USD 3.5 bn, compared with USD 1.2 bn in the prior-year period. The net loss improved to about USD 541 m.
Starlink is increasingly becoming the most important financial growth driver. Connectivity revenue reached around USD 4.3 bn in the second quarter, supported by strong subscriber growth as well as higher demand from enterprise customers and government institutions.
Performance Q2 2026
| Metric | Q2 2026 | Observation |
|---|---|---|
| Revenue | USD 7.8 bn | +92% year-over-year |
| Adjusted EBITDA | USD 3.5 bn | Strong improvement |
| Net Income | -USD 541 m | Loss decreasing |
| Connectivity revenue | USD 4.3 bn | Strong growth |
| Starlink subscribers | approx. 12 m | Continued growth |
Source: SpaceX, Q2 2026 financial report
Rating
Valuation is currently one of the biggest red flags. SpaceX set its IPO price at USD 135 per share, while Morningstar calculated a fair value of only USD 62 per share after the IPO and rated uncertainty as “Very High”.
This substantial gap shows how much of the expected future growth is already reflected in the current market valuation.
For MUMAK, this results in an important distinction:
Company quality ≠ stock valuation
The key point for MUMAK is therefore that strong company fundamentals and the valuation of the stock must be assessed separately.
Outlook 2026–2028
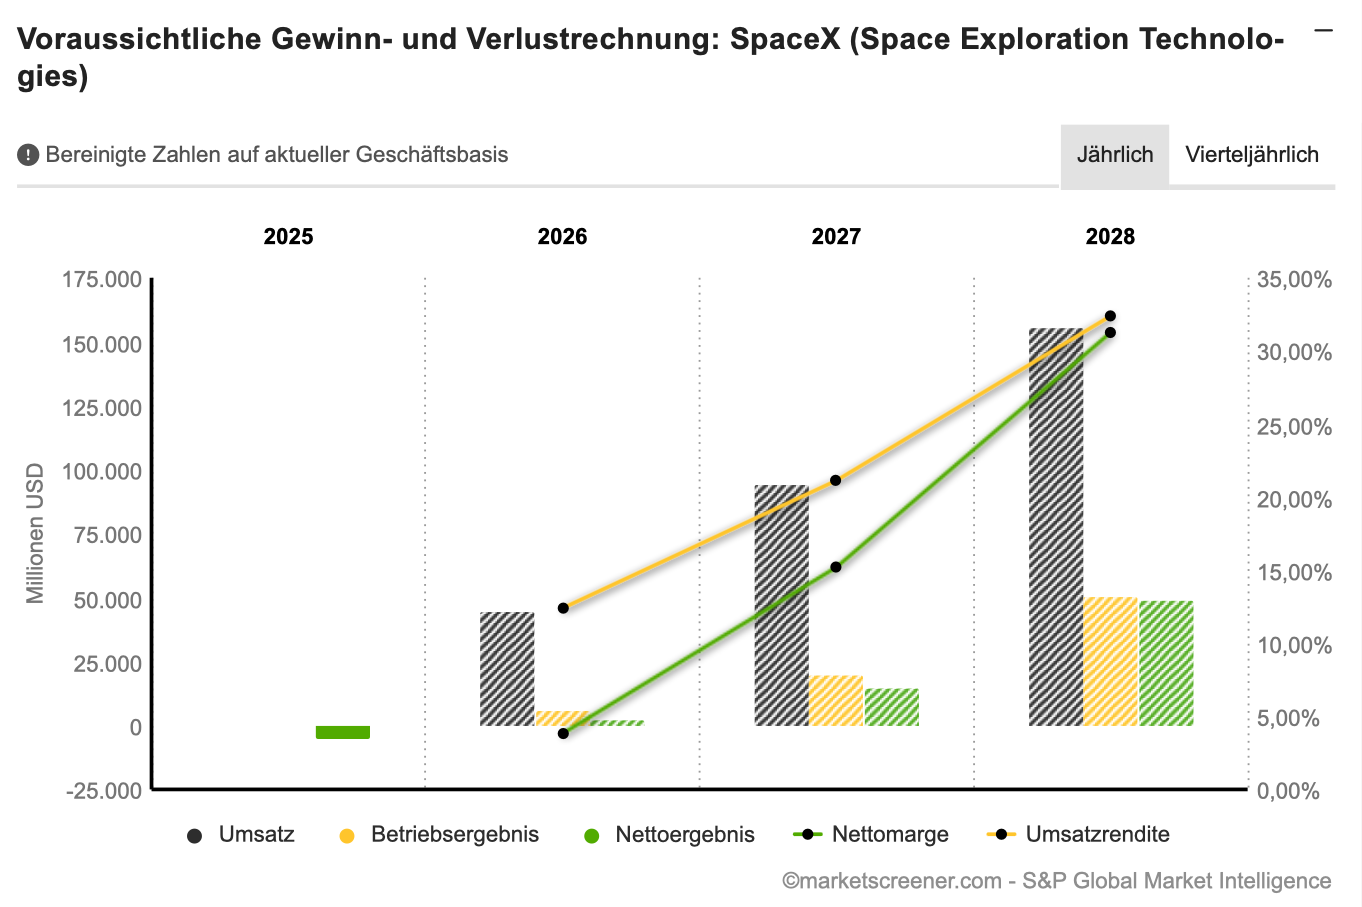
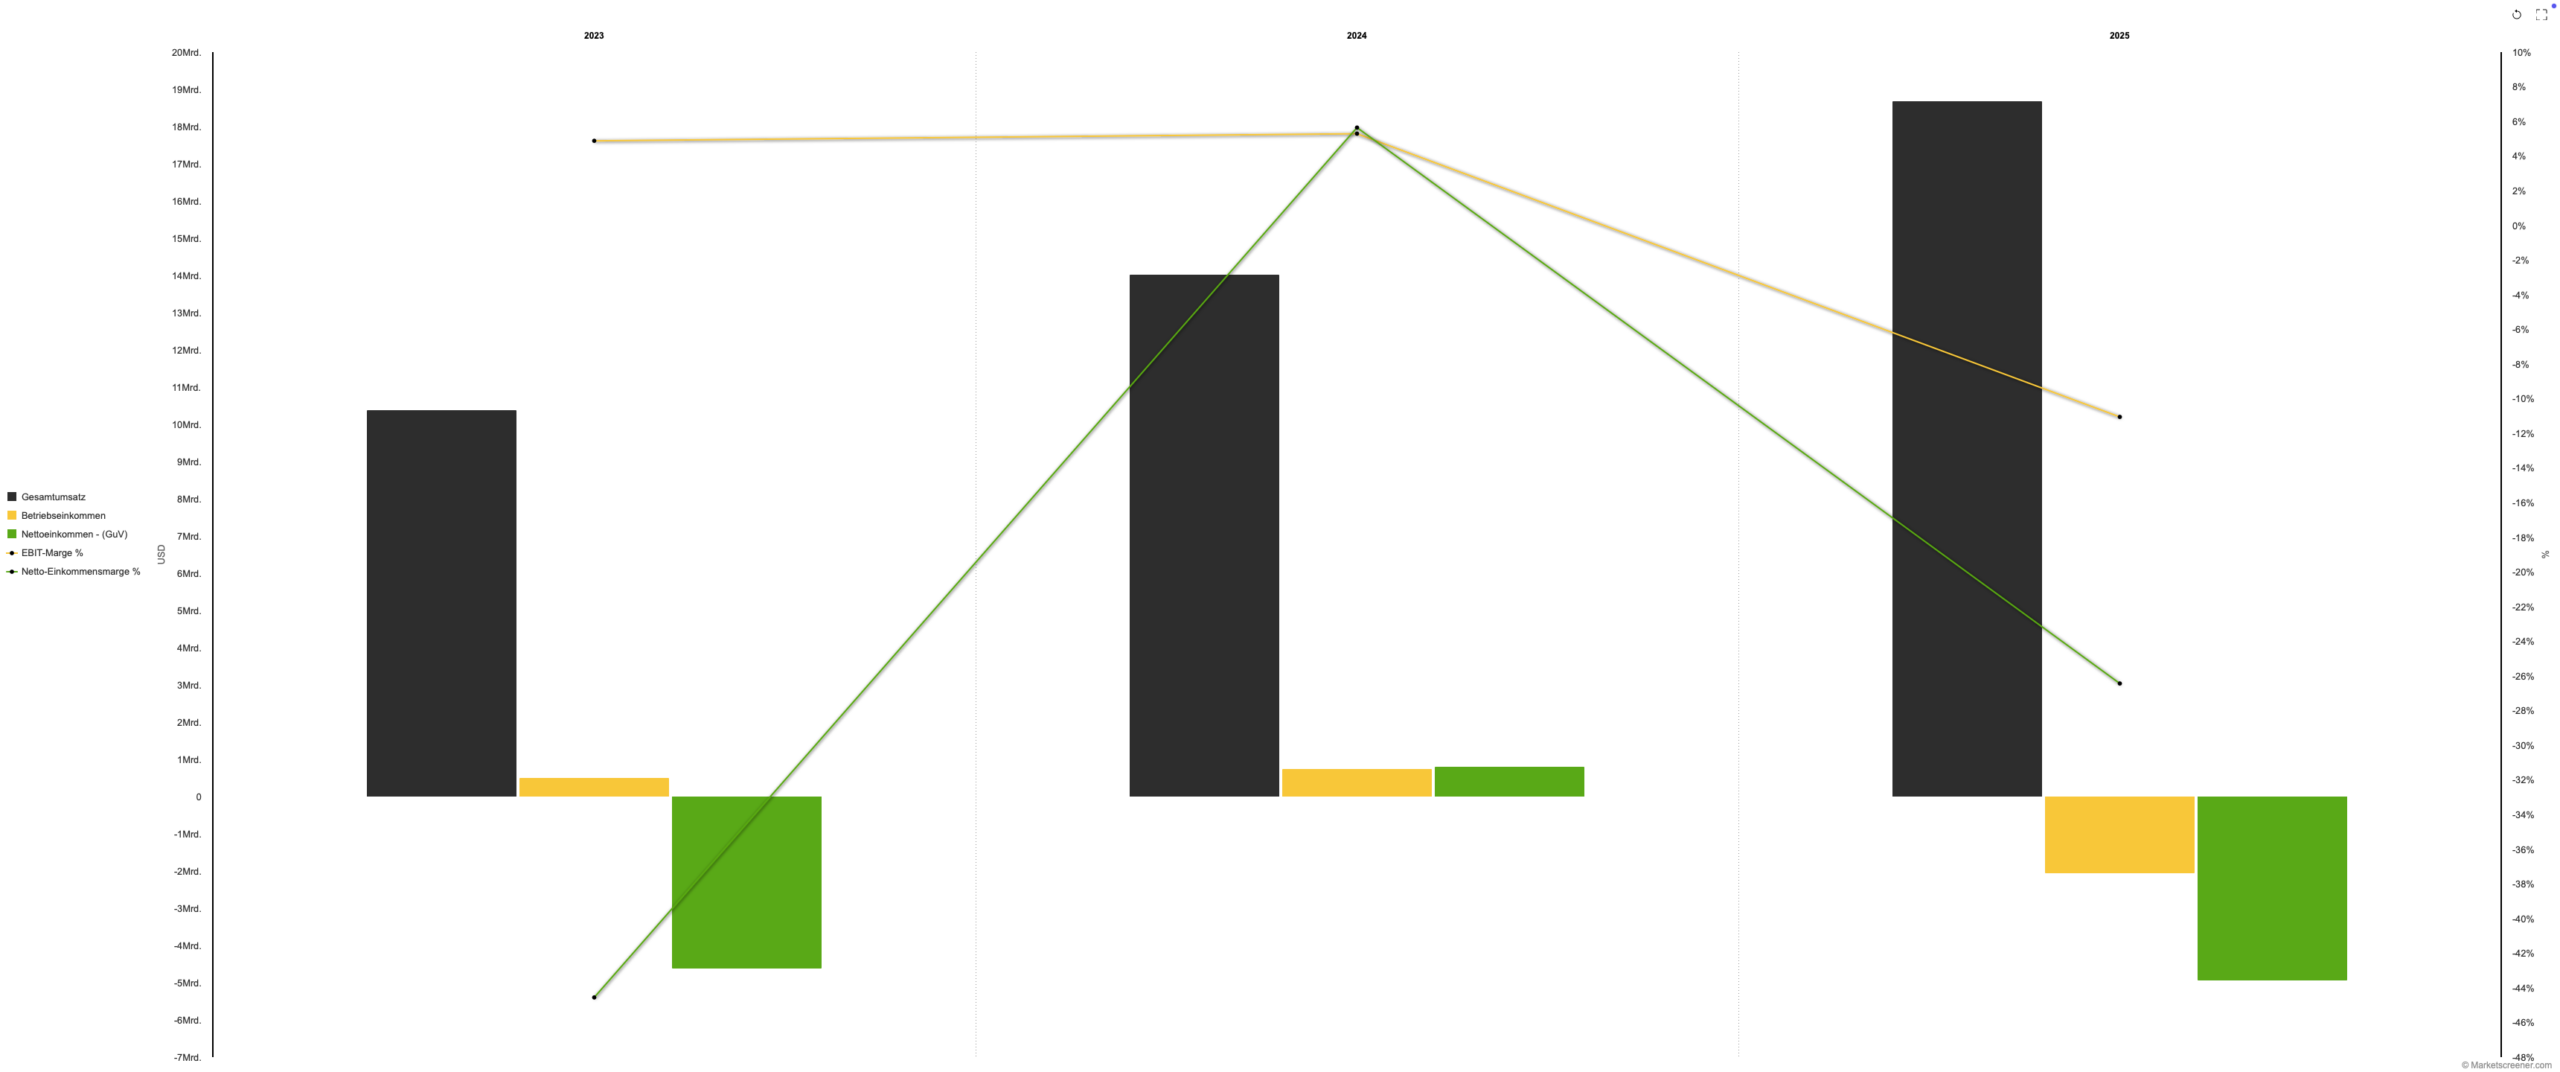
Source: Marketscreener, August 2026
Analyst estimates expect a dramatic improvement in financial performance over the next three years.
Revenue is estimated at around USD 44.6 bn for 2026. For 2027, USD 93.7 bn is projected, and for 2028, around USD 155.3 bn is expected.
This corresponds to expected revenue growth of approximately 110% in 2027 and a further 66% in 2028.
The forecast chart shown in the document on page 5 also points to a significant improvement in profitability. Operating profit and net profit are expected to rise sharply, while margins could move toward the 30% level by 2028.
Opportunities
- Strong revenue growth: Revenues are growing rapidly.
- Starlink growth: Connectivity is developing into a meaningful growth driver.
- Margin expansion: Profitability could improve significantly.
- Scale effects: Higher volumes could improve economics.
- New business areas: Starship and AI offer additional potential.
Risks
- Extreme valuation: Expectations are exceptionally high.
- High investment requirements: Expansion requires enormous capital.
- Earnings volatility: Historical earnings performance remains prone to fluctuations.
- Forecast risk: Expectations for 2027–2028 are very ambitious.
- Execution risk: Starship and AI must meet the high expectations.
Key takeaway: SpaceX offers exceptional growth potential and significant expected margin expansion. At the same time, the valuation already reflects very high expectations for future financial performance.
MUMAK.me Assessment Phase 3: Positive = 1 MUMAK
Space Exploration Technologies Corp. — SpaceX
News, Analysts, and Market Sentiment
Assessment
Since its IPO in June 2026, SpaceX has attracted significant investor attention. The shares were issued at USD 135 and have shown substantial volatility since listing.
Recently, attention has focused primarily on Starlink’s growth, Starship’s development, and the expansion into AI infrastructure. These areas could significantly increase SpaceX’s long-term growth potential.
Overall, analyst sentiment is positive. However, the very wide range of price targets shows that assessments of SpaceX’s future enterprise value diverge materially.
Analyst Consensus
| Average Recommendation | BUY |
| Number of Analysts | 35 |
| Average Price Target | approx. USD 231 |
| Upside to the average target | approx. +67% |
| Highest price target | USD 800 |
| Lowest Price Target | USD 62 |
Source: MarketScreener, retrieved in August 2026.
Interesting Fact
In March 2026, Starlink surpassed the threshold of 10,000 active satellites in low Earth orbit (LEO), making it by far the largest satellite constellation ever operated.
SpaceX reached this scale only around seven years after the start of Starlink’s operational build-out.
Opportunities
- Positive analyst view: The current consensus is “Buy”.
- Attractive price target: The average price target is around USD 231.
- Starlink growth: Further expansion supports positive market sentiment.
- Progress with Starship: Successful development could strengthen investor confidence.
- New business areas: AI offers additional growth potential.
Risks
- Wide range of price targets: Analyst expectations differ significantly.
- High expectations: Strong future growth is already priced in.
- Stock volatility: Price moves remain substantial.
- Delays with Starship: Setbacks could weigh on market sentiment.
- High news sensitivity: The stock can react strongly to new developments.
Key takeaway: Positive analyst sentiment supports SpaceX, while the wide range of price targets reflects differing expectations regarding the company’s future growth and valuation.
MUMAK.me Evaluation Phase 4: Positive = 1 MUMAK
Space Exploration Technologies Corp. — SpaceX
Technical Analysis
Assessment
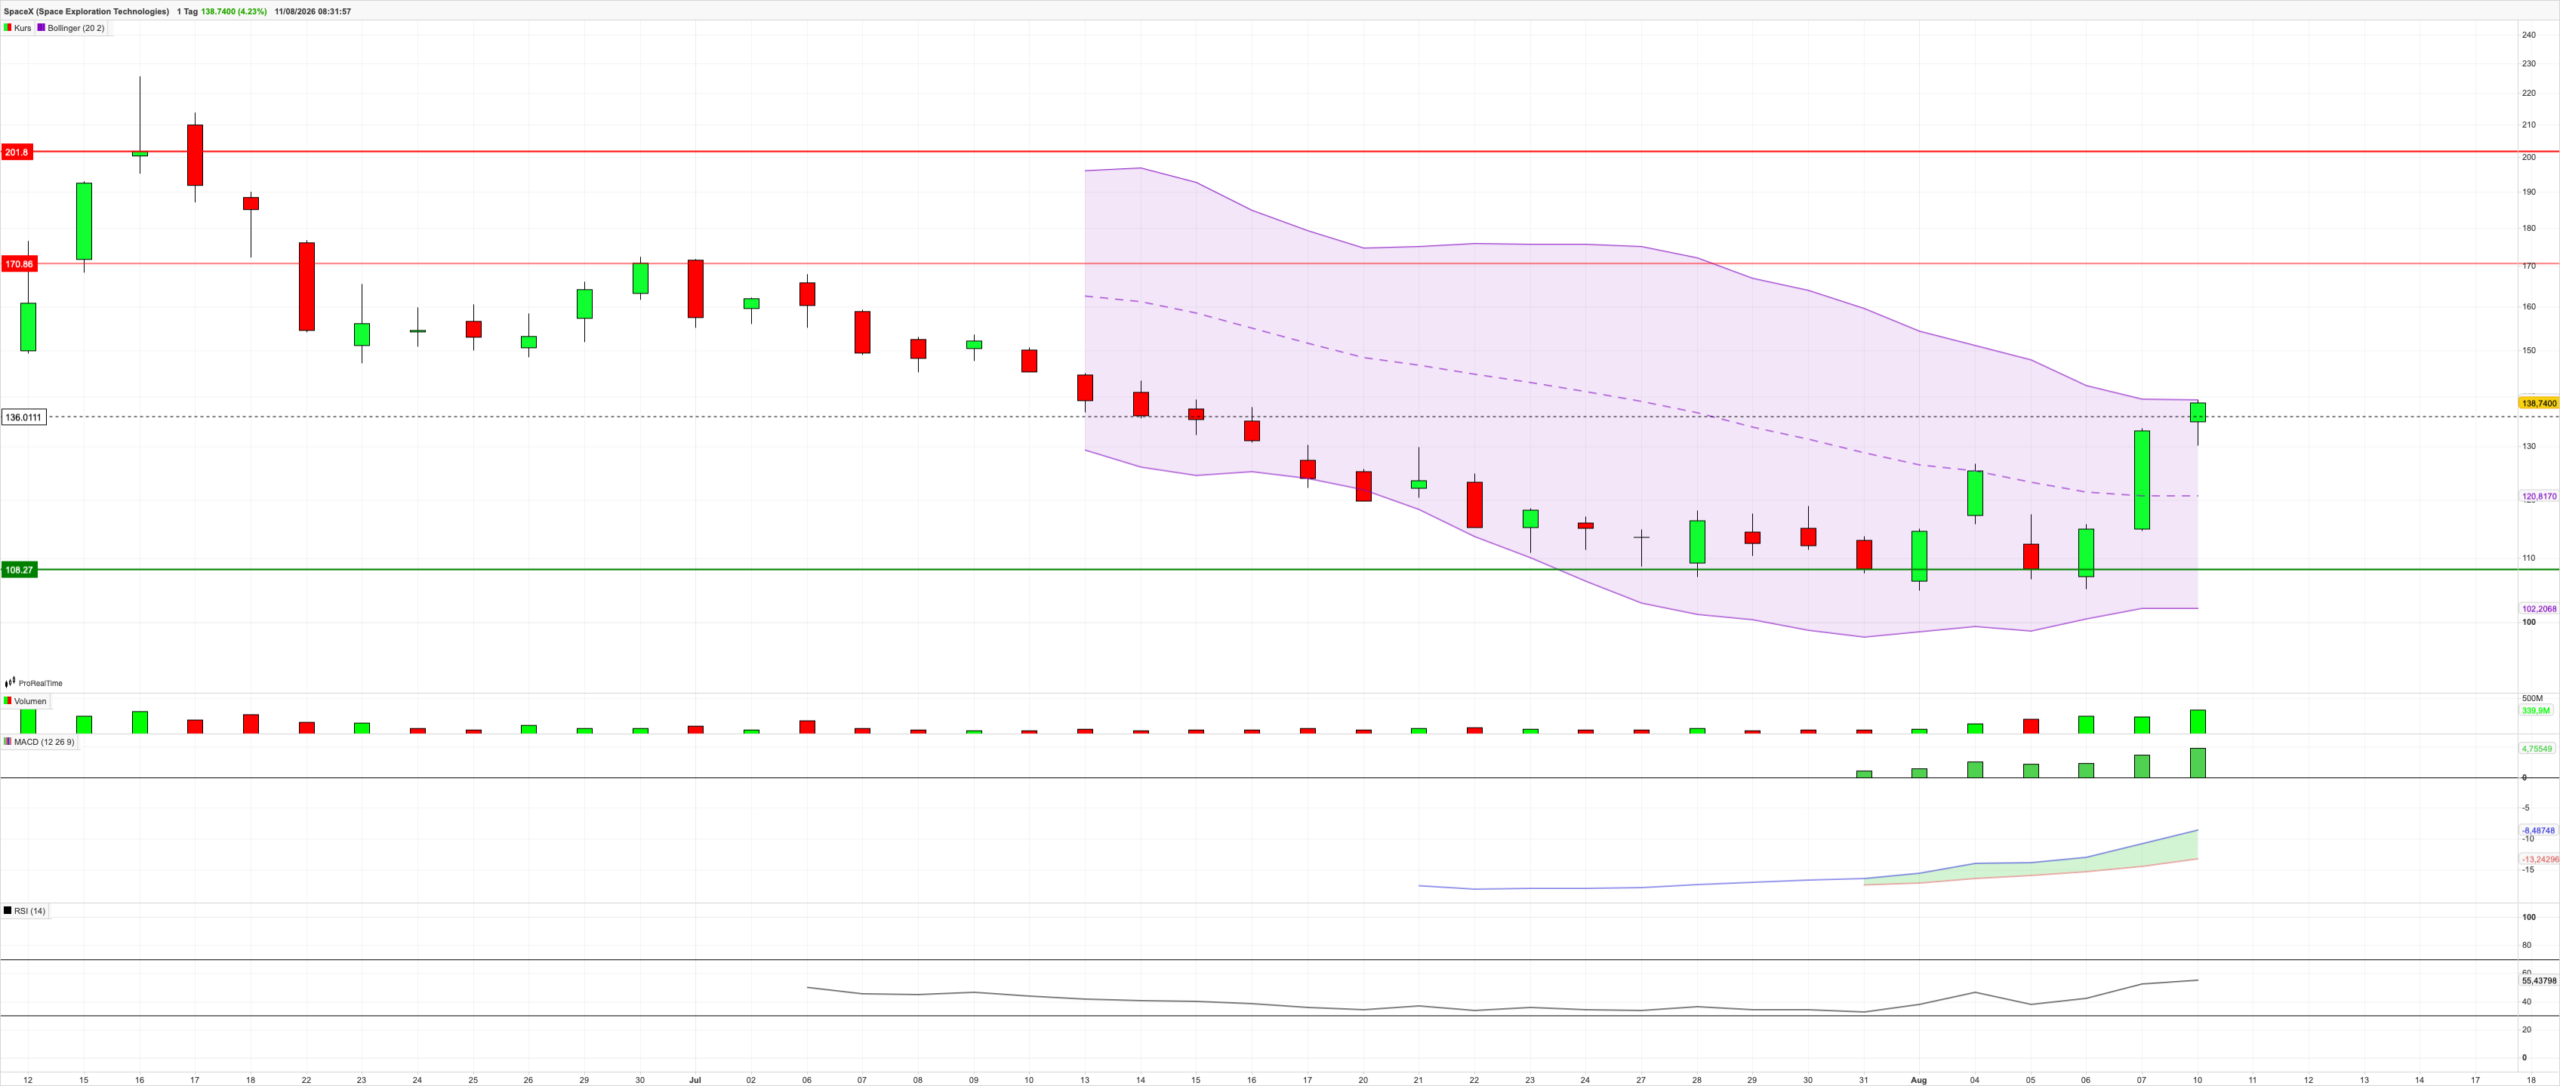
Since the IPO, the SpaceX stock has shown high volatility. After trading above USD 200 at times, the stock saw a sharp correction. It then found support around USD 108.
Most recently, the technical picture has improved. The stock recovered to around USD 139, supported by higher trading volume and increasingly positive momentum.
However, due to SpaceX’s still short trading history, the informative value of longer-term technical analysis remains limited.
| Indicator | Rating | Interpretation |
|---|---|---|
| RSI (14) | Positive | Around 55; momentum is improving without the stock being overbought. |
| MACD | Positive | The MACD is improving and supports the recent price recovery. |
| Bollinger Bands | Positive | The price has moved above the middle band and is trending toward the upper band. |
Performance over the last weeks/months (as of Aug 11, 2026)
RSI (14)
Positive
- RSI around 55: Momentum has improved.
- Balanced level: Buying pressure is increasing.
- Not overbought: The RSI remains below 70.
Interpretation: The RSI signals improved momentum without signs of an overheated market.
MACD (12/26/9)
Positive
- Improved MACD: Momentum has strengthened.
- Bullish signal: The MACD line is above the signal line.
- Still below the zero line: The broader trend has not yet fully recovered.
Interpretation: The MACD supports the recent price recovery, even though the longer-term signal still calls for caution.
Bollinger Bands (20)
Positive
- Middle band: approx. USD 121
- Upper band: approx. USD 136
- Price above the upper band: The stock has risen to around USD 139.
- Strong momentum: The recent price move points to increasing buying pressure.
Interpretation: The Bollinger Bands confirm strong short-term momentum. However, a price above the upper band could also lead to consolidation.
Opportunities
- Improved momentum: The recovery is gaining strength.
- Healthy RSI: Momentum is positive, but not yet excessively strong.
- Higher trading volume: Recent price gains are receiving stronger support.
- Breakout above USD 136: Reinforces the technical recovery signal.
Risks
- Short trading history: Technical signals are still less reliable.
- High volatility: Large price moves persist.
- Resistance around USD 170: Could limit further recovery.
- Support around USD 108: A break below this level would worsen the technical picture.
Key takeaway: SpaceX is showing improved short-term momentum. However, given the short trading history and high volatility, caution remains warranted in the technical assessment.
MUMAK.me Rating Phase 5: Positive = 1 MUMAK
Space Exploration Technologies Corp. — SpaceX
What speaks in favor of SpaceX?
- Strong market position: SpaceX is among the world’s leading providers of rocket launch services.
- Starlink growth: Satellite-based connectivity is developing into an important financial growth driver.
- Vertical integration: SpaceX controls rockets, satellites, and network services.
- Strong revenue growth: Revenues are growing rapidly.
- Improving profitability: Operating performance is expected to improve significantly.
- Strategic importance: SpaceX plays an important role within U.S. space and defense infrastructure.
- Starship potential: Successful commercialization could further reduce launch costs and open up new markets.
- Improved technical picture: RSI, MACD, and Bollinger Bands currently support the price recovery.
What speaks against SpaceX?
- High valuation: The current valuation already reflects strong expectations for future growth.
- High capital requirements: Starship, satellites, and AI infrastructure require substantial investment.
- Earnings volatility: Historical earnings performance has not yet been consistent.
- Execution risk: Starship remains a technically extremely complex program.
- Ambitious forecasts: Financial expectations through 2028 are very high.
- Intensifying competition: Competitors in rocket launches and satellites continue to expand their activities.
- Short trading history: Long-term technical analysis remains limited.
- High stock volatility: Since the IPO, the stock has recorded large price swings.
What we are monitoring
- Development and growth of Starlink.
- Revenue and margin development versus the forecasts for 2026–2028.
- Development of the AI infrastructure and its contribution to future growth.
- Government and defense contracts, especially Starshield.
- Analyst estimates and changes in price targets.
Summary
SpaceX combines several major growth areas within one company: reusable launch systems, satellite communications, defense infrastructure, and next-generation space technologies.
Starlink is developing into an increasingly important financial growth driver, while Starship could significantly expand the company’s long-term opportunities. Strong revenue growth and the expected improvement in margins support the fundamental outlook.
At the same time, SpaceX must deliver on the high expectations. The company must continue scaling Starlink and successfully commercialize Starship.
The outlook therefore remains positive; however, future performance will depend on whether SpaceX succeeds in translating its technological leadership into sustainable growth, profitability, and cash flow.
Rating According to the MUMAK Method
| Category | Rating |
|---|---|
| Geopolitics | Positive |
| Industry | Positive |
| Fundamentals | Positive |
| News & Sentiment | Positive |
| Technical Analysis | Positive |
Overall Rating


