

TKMS AG & Co. KGaA
TKMS is one of Europe’s most strategically important maritime defense groups. The Kiel-based company develops and builds conventional submarines, surface combatants, and specialized naval vessels. Through Atlas Elektronik, TKMS also supplies sonar systems, sensors, torpedoes, guidance systems, and maritime electronics.
The company’s prospects are increasingly shaped by rising procurement programs in Europe and NATO’s maritime defense sector. TKMS’s order backlog amounted to approximately €20.1 billion after the first nine months of fiscal year 2025/26, compared to €18.2 billion at the end of fiscal year 2024/25.
The Canadian Patrol Submarine Project represents one of the largest potential business opportunities in the company’s history. Canada has selected TKMS as the preferred bidder for up to twelve submarines based on the Type 212CD platform.
Operational momentum has significantly increased. In the first nine months of fiscal year 2025/26, revenue rose by 19% to €1.890 billion.
Assessment
This analysis evaluates TKMS according to the UMBRELLA strategy using the MUMAK method.
The evaluation is carried out across five decision phases: Geopolitics, Industry, Fundamentals, Market Sentiment, and Technical Analysis.
The goal is not to predict the future precisely. The goal is to provide orientation. We classify facts, show their interdependencies, and structure a comprehensible decision logic.
We explain – you decide.
Geopolitics
Context
TKMS benefits from the rebuilding of European and NATO naval forces. Submarines, anti-submarine warfare systems, maritime surveillance, and the protection of vital sea lanes in the Atlantic and Baltic Seas have gained significant priority in defense spending.
The Type 212CD submarine program is a central growth driver for TKMS. Germany and Norway are already utilizing the program, and Norway increased its order to six submarines in January 2026. In July, Canada selected Team 212CD as the preferred bidder for up to twelve submarines. If a final agreement is reached, Germany, Norway, and Canada could operate submarines based on the same platform.
Opportunities
- Rising European defense spending: Higher defense budgets support demand for submarines, frigates, and naval systems.
- Growing NATO cooperation: Germany, Norway, and potentially Canada could deploy the Type 212CD submarine.
- Opportunity in Canada: Canada has selected TKMS as the preferred bidder for its new submarine program.
- Modernization of the German Navy: Germany is investing in new submarines and frigates.
- Strategic importance: Maritime defense is gaining importance in the Baltic Sea and the North Atlantic.
- International expansion: Projects in Canada and India could reduce dependence on the German market.
Risks
- Dependence on government budgets: The majority of TKMS orders depend on public defense spending.
- Political delays: Large military projects can be postponed.
- Long procurement processes: The conclusion of large contracts can take several years.
- Changing priorities: Elections or political shifts can influence defense spending.
- Export restrictions: European regulations can restrict sales to certain countries.
Key Takeaway: Higher defense spending and stronger NATO cooperation support TKMS, but large orders remain dependent on political decisions.
MUMAK.me Rating Phase 1: Positive = 1 MUMAK
TKMS AG & Co. KGaA
Industry
Classification
After years of limited investment in many NATO fleets, maritime defense is entering a phase of significantly higher spending. Demand for submarines, frigates, sonar systems, underwater weapons, and naval electronics is rising – all core business areas for TKMS.
TKMS is expanding its capacities in Wismar and working with international shipyards and technology partners. Atlas Elektronik also strengthens the Group’s position in naval electronics and integrated systems.
Valuation Comparison
| Key Figure | TKMS 2026e | European Defense/Marine Peer Group* | Valuation |
|---|---|---|---|
| P/E Ratio | 39.5x | approx. 24-32x | Weaker |
| EBIT Margin | 6.5% | approx. 8-12% | Weaker |
| Net Margin | 6% | approx. 6-9% | Weaker |
| Revenue Growth | approx. 5% | approx. 7-12% | Weaker |
*The peer group includes selected European defense and naval companies, including BAE Systems, Fincantieri, Saab, and Thales. Source: MarketScreener consensus.
Opportunities
- Growing market for maritime defense: European countries are increasing investment in submarines, frigates, and naval technology.
- Strong market position: TKMS is one of the leading providers of non-nuclear submarines.
- High barriers to entry: Building modern submarines requires advanced technology and decades of experience.
- Large order backlog: An order backlog of more than EUR 20 billion offers high visibility for future business.
- Naval electronics: Sensors, sonar, and electronic systems broaden the TKMS product portfolio.
- Long-term service business: Maintenance and modernization can generate revenue for decades after delivery.
Risks
- Limited production capacities: Shipyards can only build a limited number of vessels simultaneously.
- Shortage of skilled labor: Naval shipbuilding requires highly specialized employees.
- Complex supply chains: Delays in components can slow down large projects.
- Strong competition: European and international shipbuilders compete for large naval contracts.
- Long delivery times: Building submarines and frigates can take many years.
- Rising costs: Higher labor and material costs can weigh on profitability.
Key Takeaway: Rising naval spending and TKMS’s strong position in the submarine sector support the company, while production capacities and complex projects remain key challenges.
MUMAK.me Rating Phase 2: Positive = 1 MUMAK
TKMS AG & Co. KGaA
Fundamentals
Context
TKMS achieved revenue of approximately €1.9 billion, representing a 19% increase year-over-year.
Adjusted EBIT rose to €110 million, compared to €98 million in the prior-year period.
Particularly important is the significant upward revision of the full-year revenue forecast. TKMS now expects revenue growth of 10–12% for fiscal year 2025/26, compared to the previous forecast of 2–5%.
The more optimistic outlook particularly reflects the positive development at ATLAS ELEKTRONIK and in the Surface Vessels segment, while moderate growth is expected for the submarine business.
Financial Performance – 9M FY 2025/26
| Key Figure | 9M FY 2025/26 | 9M FY 2024/25 | Change |
|---|---|---|---|
| Revenue | EUR 1.890 billion | EUR 1.587 billion | +19% |
| Adjusted EBIT | EUR 110 million | EUR 98 million | +13% |
| Adjusted EBIT Margin | 5.8% | 6.1% | −0.3 percentage points |
| Order Intake | EUR 3.409 billion | EUR 5.597 billion | −39% |
| Order Backlog | EUR 20.6 billion | EUR 18.2 billion | +13% |
| Free Cash Flow | −EUR 72 million | +EUR 756 million | −EUR 828 million |
The decline in order intake should not be interpreted as a deterioration of underlying demand.
The prior-year comparison was exceptionally high, as TKMS received several major orders, including the expansion of the German-Norwegian Type 212CD program and the order for the new research vessel Polarstern.
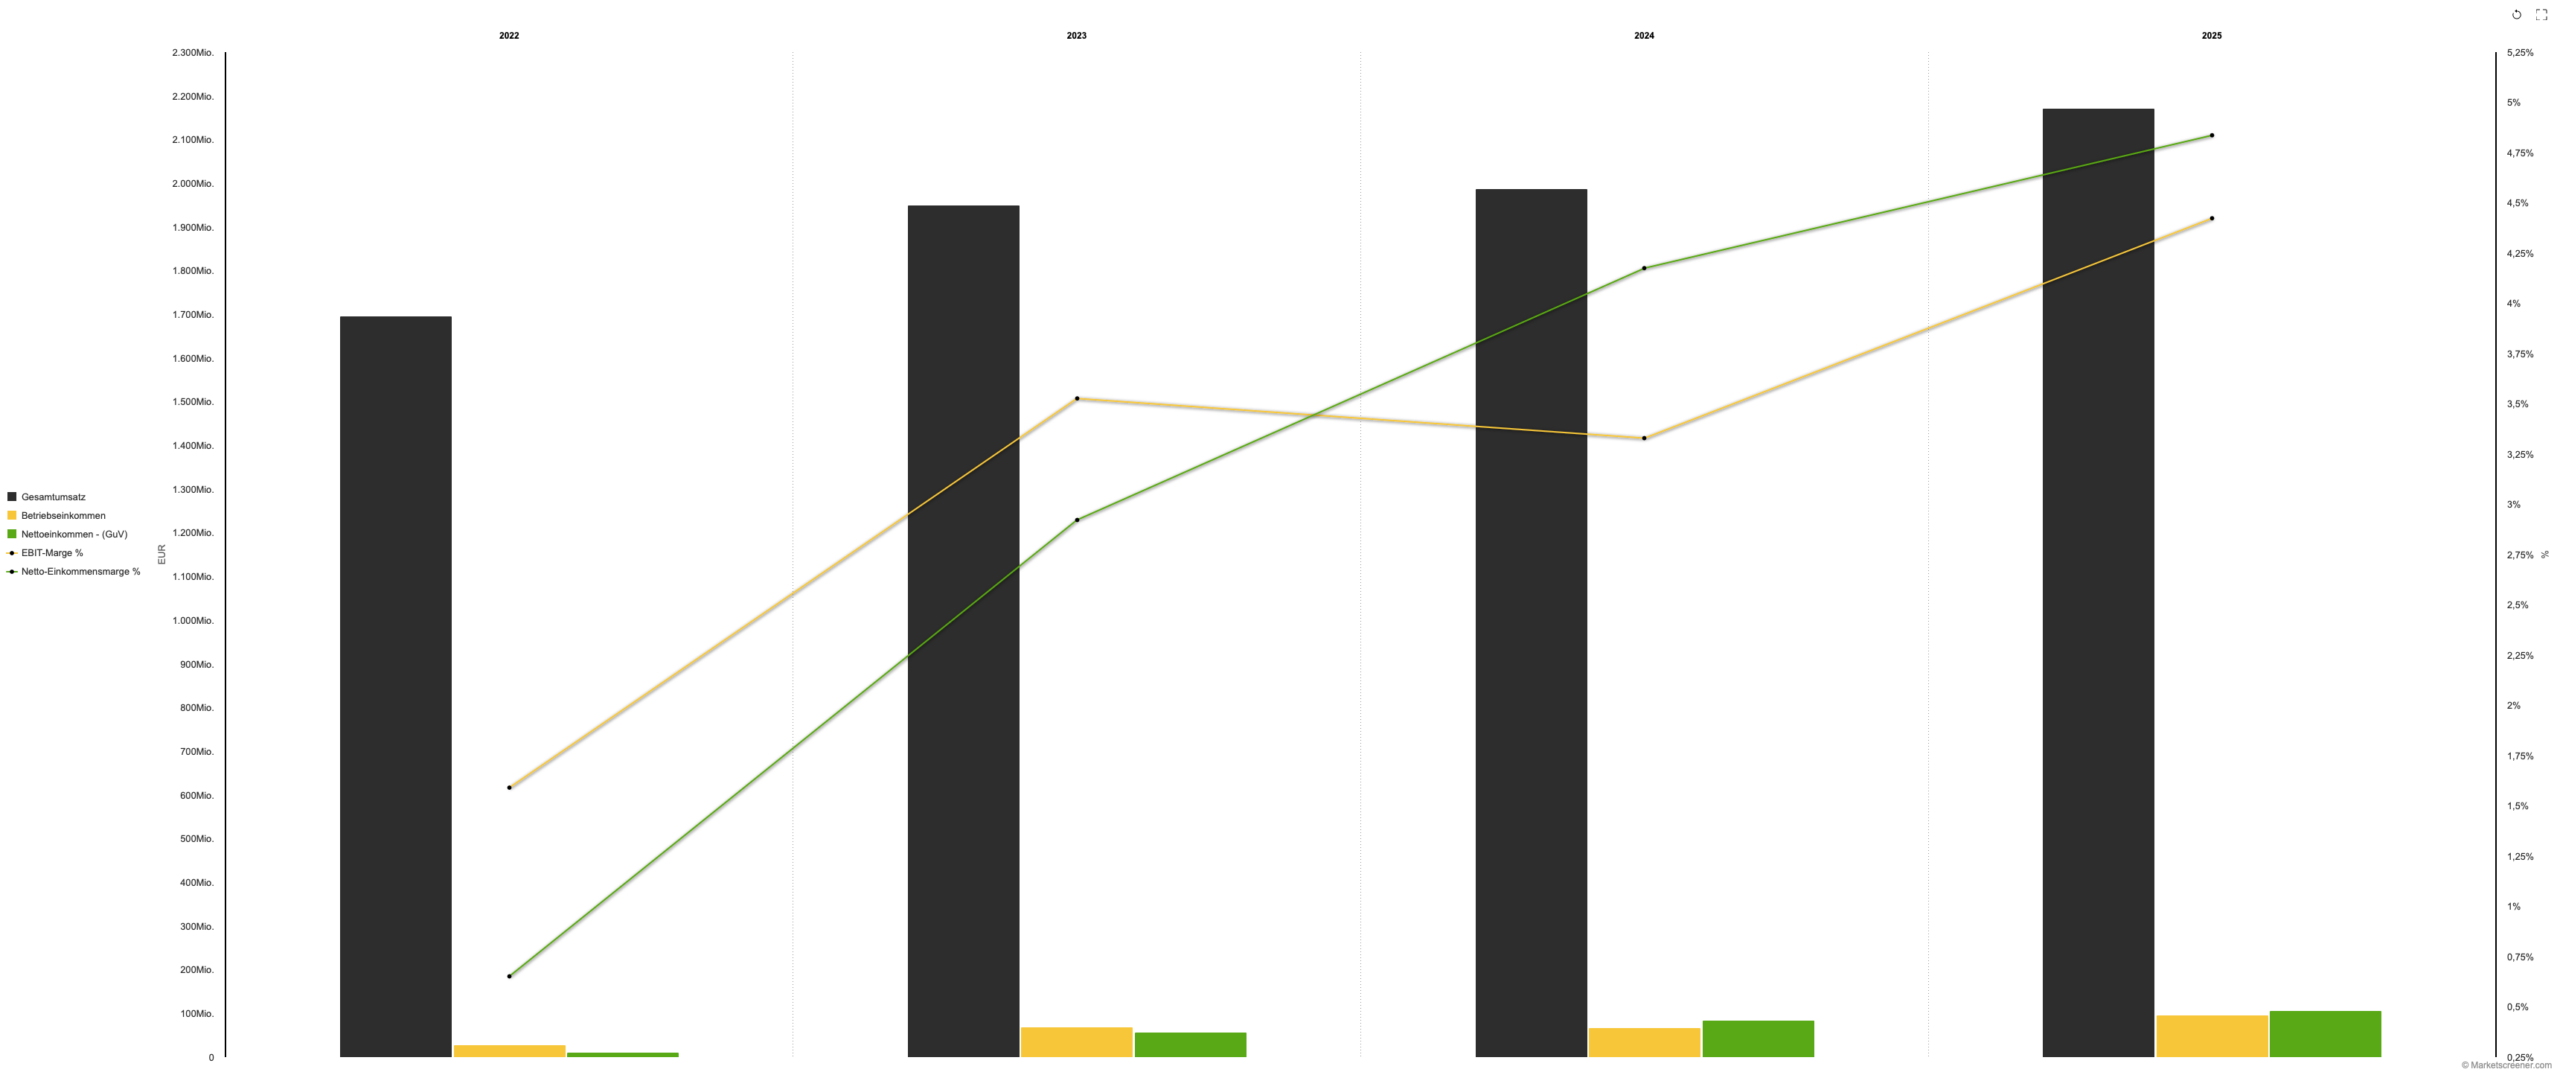
Historical Financial Performance
TKMS recorded continuous revenue growth and was able to significantly increase profitability compared to previous years.
Updated Outlook
Following the strong results of the first nine months, TKMS has raised its forecast for fiscal year 2025/26.
| Forecast | New Outlook | Previous Outlook |
|---|---|---|
| Revenue Growth | +10–12% | +2–5% |
| Adjusted EBIT Margin | up to 6.5% | over 6% |
| Mid-term Revenue Growth | Confirmed | approx. 10% annually |
| Mid-term EBIT Margin | Confirmed | above 7% |
| Strategic Investments | Unchanged | approx. €200 million |
| Dividend Policy | First distribution targeted for 2027 | 30–50% of net profit |
Opportunities
- Accelerated Revenue Growth: Revenue in the first nine months increased by 19%.
- Raised Forecast: Management increased the forecast for revenue growth in fiscal year 2025/26.
- High Order Backlog: Orders totaling approximately €20.1 billion ensure high revenue visibility.
- Large Future Orders: Programs in Canada, Germany, India, and other countries could significantly increase the order backlog.
- Growth at Atlas Elektronik: The marine electronics segment offers an additional growth driver.
Risks
- Margin Development: The adjusted EBIT margin declined in the first nine months despite strong revenue growth.
- Long Project Durations: Revenues from naval orders are realized over many years.
- Cash Flow Volatility: Milestone payments from customers can lead to significant fluctuations in free cash flow.
- High Implementation Requirements: Current forecasts assume a successful expansion of production capacities.
Key Takeaway: The Q3 results significantly strengthen TKMS’s fundamental outlook.
MUMAK.me Rating Phase 3: Positive = 1 MUMAK
TKMS AG & Co. KGaA
News, Analysts, and Market Sentiment
Context
Recent news has strengthened TKMS’s position. The most significant development occurred in July when Canada selected Team 212CD as the preferred bidder for a potential program of twelve submarines. Delivery of the first submarine is currently scheduled for 2033.
Germany has also advanced plans to purchase four MEKO A-200 DEU frigates with an option for additional vessels. TKMS is also pursuing projects and partnerships in markets such as India, Spain, Greece, and Brazil.
The Q3 results provide another positive impetus for market sentiment.
Analyst Consensus
| Average Recommendation | ACCUMULATE |
| Number of Analysts | 7 |
| Average Price Target | approx. EUR 100 |
| Potential to Average Target | approx. +13% |
| Highest Price Target | EUR 140 |
| Lowest Price Target | EUR 76 |
Source: MarketScreener, retrieved August 2026.
Interesting Fact
The Canadian program alone could increase TKMS’s existing order backlog of €20.6 billion by more than 50%. If the contract is signed, it would be the largest single order in TKMS’s history and could support production, maintenance, and partnership revenues for decades.
Opportunities
- Strong Q3 Results: Revenue increased by 19%, while adjusted EBIT grew by 13%.
- Raised Forecast: Management significantly increased its growth expectations for fiscal year 2025/26.
- Canadian Submarine Project: TKMS was selected as the preferred bidder for up to twelve Type 212CD submarines.
- Order Backlog Potential: The Canadian project could increase the current order backlog by more than 50%.
- German Frigate Program: Germany approved four MEKO A-200 DEU frigates with an option for additional units.
Risks
- Canada not yet final: The status as preferred supplier is important, but the final contract still needs to be concluded.
- High expectations: Positive news has already raised expectations for future growth.
- News sensitivity: Delays in major defense projects could quickly dampen market sentiment.
- Limited stock market history: TKMS has only been listed since 2025, making long-term market behavior still difficult to assess.
Key takeaway: Q3 strengthens the positive market sentiment surrounding TKMS.
MUMAK.me Rating Phase 4: Positive = 1 MUMAK
TKMS AG & Co. KGaA
Technical Analysis
Context
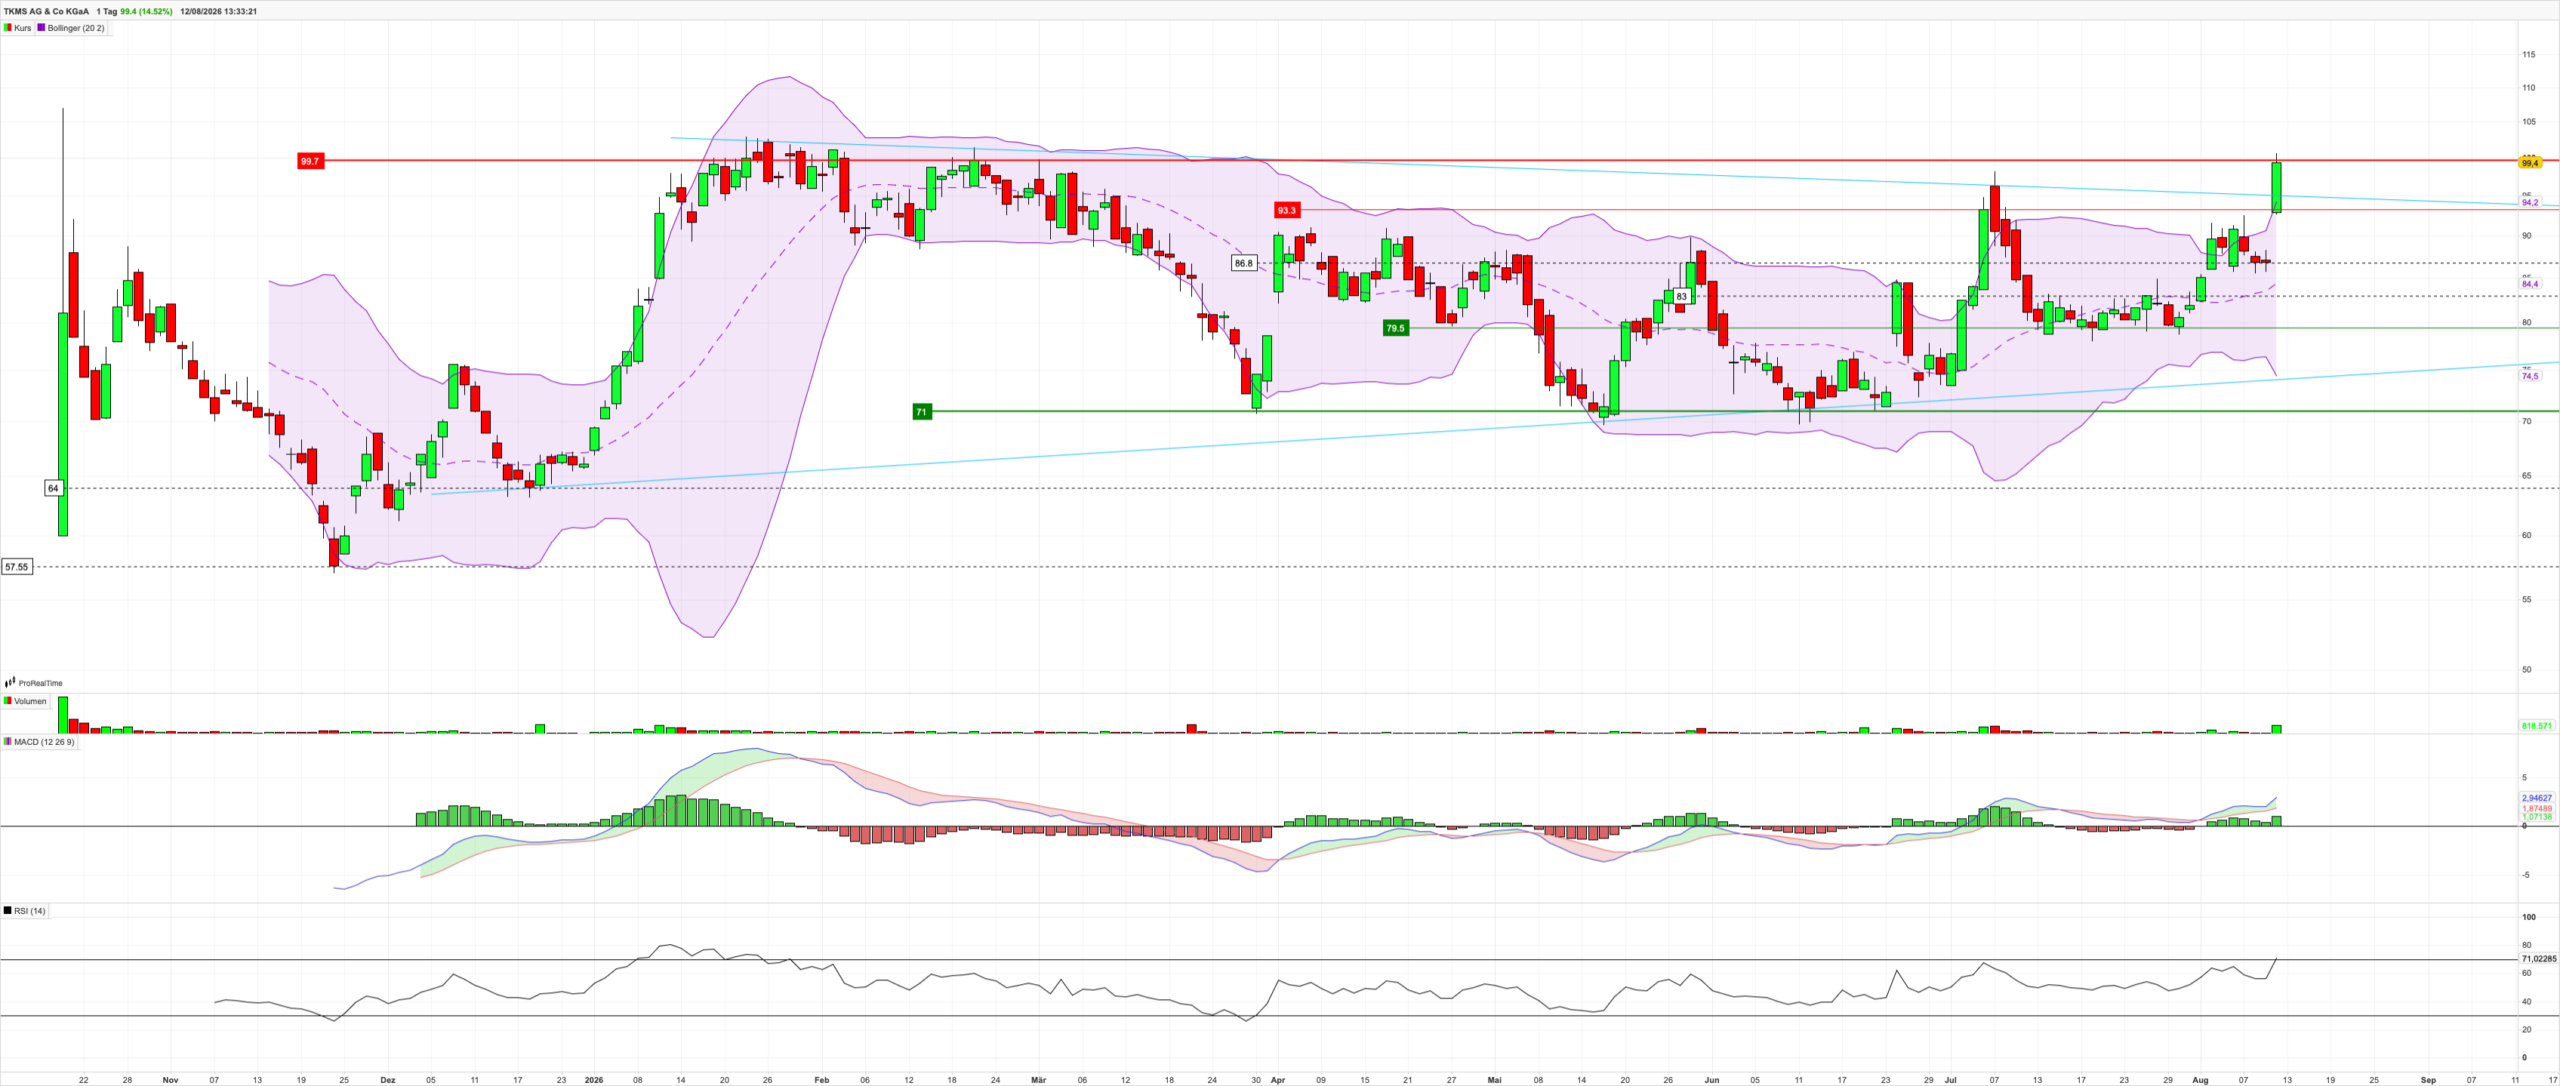
The TKMS share has recovered significantly after the recent consolidation phase. After finding support in the range of €79.5–83, the share rose sharply and is currently trading at approximately €99.4.
The recent price movement is technically significant, as the share has broken above the previous resistance area at €93–94 and is now testing the important resistance at approximately €99.7, which roughly corresponds to the previous high.
| Indicator | Rating | Interpretation |
|---|---|---|
| RSI (14) | Positive | The daily RSI has risen to around 71, placing it slightly in overbought territory. |
| MACD | Positive | The MACD provides a bullish signal. |
| Bollinger Bands | Positive | The share price has risen sharply towards the upper Bollinger Band and slightly exceeded it. This is another sign of strong buying momentum. |
Performance over the last weeks/months (as of Aug 12, 2026)
RSI (14)
Positive
- RSI at approx. 71: Buying momentum has increased.
- Above 70: The indicator has slightly entered the overbought zone.
- Strong Momentum: The high RSI confirms the strength of the recent breakout.
Interpretation
The RSI confirms strong upward momentum.
MACD (12/26/9)
Positive
- Positive MACD: The MACD remains above the zero line.
- Bullish Positioning: The MACD line remains above the signal line.
- Increasing Momentum: Recent developments show a renewed acceleration of positive momentum.
Interpretation
The MACD provides a clear positive technical signal.
Bollinger Bands (20)
Positive
- Strong Breakout: The stock has risen above the upper Bollinger Band.
- Increasing Momentum: The breakout confirms strong short-term buying pressure.
- Higher Volatility: The widening bands reflect the recent stronger price movements.
Interpretation
The Bollinger Bands confirm the strength of the current price movement. However, the position above the upper band also suggests that the stock is technically overextended and could consolidate before another sustained upward impulse occurs.
Opportunities
- Breakout above €93–94: The stock has overcome an important resistance zone.
- Strong Momentum: Both price performance and MACD support the current uptrend.
- Testing Previous High: TKMS is approaching the important resistance level at €99.7.
Risks
- High Volatility: TKMS shares can react strongly to order and company news.
- RSI above 70: The stock has slightly entered the overbought zone.
- Overextended Position on Bollinger Bands: The quotation above the upper Bollinger Band increases the likelihood of short-term consolidation.
Key Takeaway: The technical picture for TKMS has significantly improved.
MUMAK.me Rating Phase 5: Positive = 1 MUMAK
TKMS AG & Co. KGaA
Rating According to the MUMAK Method
What speaks for TKMS?
- An order backlog of EUR 20.1 billion provides TKMS with high revenue visibility for many years.
- Revenue increased by 19% in the first nine months, while adjusted EBIT grew by 13%.
- Management has significantly raised its forecast for revenue growth in fiscal year 2025/26.
- Atlas Elektronik offers additional growth potential in marine electronics, sensor technology, and software.
- Potential major projects in Canada, India, and Germany could significantly increase the existing order backlog in the coming years.
What speaks against TKMS?
- The adjusted EBIT margin slightly decreased despite strong revenue growth.
- The Canadian submarine program is not yet a final contract, so its scope, timeline, and financial terms remain uncertain.
- The stock is trading at a premium compared to several established European defense companies. High expectations increase the downside potential if future developments disappoint.
- TKMS has only a short history as an independently listed company, which limits long-term comparisons and technical analyses.
What we are monitoring
- The further progress of the MEKO A-200 DEU Frigate Program.
- The development of the Indian submarine project.
- Progress on the F127 Frigate Program.
- The reactions and new analyst assessments after the Q3 results.
Summary
The Q3 results further strengthen TKMS’s fundamental outlook. Revenue growth has accelerated, management has significantly raised its forecast for FY2025/26, and the order backlog of €20.1 billion provides high revenue visibility for the coming years.
Major projects in Canada, Germany, and India could further increase the order backlog and create additional long-term growth potential. The crucial question now is whether TKMS can successfully convert this potential into new orders, increasing revenues, and higher profits.
| Category | Rating |
|---|---|
| Geopolitics | Positive |
| Industry | Positive |
| Fundamentals | Positive |
| News & Sentiment | Positive |
| Technical Analysis | Positive |
Overall Rating


